GrowthCraft

Startups

Startup founder reviewing customer feedback and business decisions at a desk

Your Startup Is Not Your Identity: Developing the Mindset to Make Better Business Decisions

Startup founder reviewing customer feedback and business decisions at a desk
A strong founder mindset means learning from business setbacks without allowing them to define your identity.

Your Startup Is Not Your Identity: Developing the Mindset to Make Better Business Decisions

For first-time startup founders, building a business is rarely just a professional undertaking. It is personal. The idea may represent years of experience, a long-held ambition, a solution to a problem that has frustrated you for years, or the opportunity to finally build something on your own terms. You invest your time, money, reputation, and energy into making it work.

That personal investment can be a powerful source of motivation. It can also become one of the biggest obstacles to making good business decisions.

When your startup becomes part of your identity, customer criticism can feel like a personal attack. A disappointing sales month can feel like evidence that you are not capable. Changing your business model can feel like admitting defeat, and walking away from an idea can feel like giving up on yourself.

These reactions are understandable, especially when you are building a company for the first time. But successful entrepreneurship requires the ability to distinguish between your worth as a person and the performance of your business.

Your startup is something you are building, not a definition of who you are. Learning to maintain that distinction helps you make clearer decisions, respond to setbacks constructively, and build a business based on evidence rather than emotion.

For early-stage founders, this mindset is not simply about personal well-being. It is a practical business skill that can influence product development, customer relationships, financial decisions, and long-term company survival.

Why Founders Become Emotionally Attached to Their Businesses

Entrepreneurs often begin with a personal connection to their ideas. Perhaps they have identified an underserved market, experienced a problem firsthand, or developed a solution they genuinely believe could make a difference. That connection creates commitment, which is valuable when the business encounters its first obstacles.

However, the longer a founder works on an idea, the easier it becomes to confuse the effort invested with the value of the idea itself. Time, money, sacrificed weekends, and personal relationships can all contribute to the feeling that the business must succeed because so much has already been invested in it.

Psychologists describe a related phenomenon as the sunk cost fallacy. People tend to continue investing in a decision because of resources they have already spent, even when the evidence suggests that continuing may not be worthwhile. In a startup, this might mean spending another six months developing a product customers have repeatedly declined to purchase simply because the founder has already spent a year building it.

Founders can also experience identity fusion, where personal identity becomes closely tied to a group, mission, or shared endeavor. When a company becomes central to how someone sees themselves, business outcomes can begin to feel like judgments of personal value.

This attachment is not inherently bad. Passion helps founders persevere when the work is difficult. The challenge is learning to use passion as fuel without allowing it to replace sound judgment.

The goal is not to care less about your startup. It is to care enough about its success to evaluate it honestly.

The Difference Between Confidence and Stubbornness

Confidence and stubbornness can look remarkably similar from the outside. Both may involve defending an idea, continuing through difficult circumstances, and refusing to give up at the first sign of trouble. The difference is how each responds to new information.

Confidence means believing you can solve problems, learn new skills, and adapt when circumstances change. A confident founder can acknowledge that a product is not working, ask why, and revise the approach without feeling that the entire entrepreneurial journey has been invalidated.

Stubbornness, by contrast, means treating a particular decision as something that must be defended, even when evidence increasingly suggests it is wrong. A stubborn founder may dismiss customer feedback, blame every failed sale on the prospect, or interpret every setback as a reason to work harder on the same approach.

Research on entrepreneurial decision-making and learning reinforces the importance of experimentation and adaptation. The U.S. Small Business Administration’s guidance on market research emphasizes understanding customers, demand, market size, and competitive conditions before making business decisions.

The practical lesson is straightforward: confidence should apply to your ability to learn and adapt, not to the assumption that your original idea must be correct.

A useful question to ask yourself is, “What evidence would convince me to change my mind?” If you cannot identify any evidence that would change your decision, you may be protecting your ego rather than evaluating the business objectively.

Separating Yourself From Your Idea

One of the most useful mindset shifts a founder can make is recognizing that an idea is a hypothesis, not a verdict on personal ability.

Your original concept is your best current guess about a problem, a customer, and a solution. It is not a promise that the market will respond exactly as you expect. The market may confirm your assumptions, reveal a better opportunity, or show that the problem is less urgent than you believed.

This is the logic behind the Lean Startup methodology, which emphasizes building, measuring, and learning through experiments. Rather than assuming your initial plan is correct, you test it, measure what happens, and use the results to decide whether to persevere, adjust, or change direction.

Consider a founder who spends eight months developing an app before asking potential customers to pay for it. The product may be technically impressive, but customers might not see enough value to justify the price. The founder now faces a choice: continue adding features in the hope that adoption will improve, or investigate what customers actually need.

The second option requires humility, but it also offers a better chance of building a viable business.

Separating yourself from your idea allows you to say, “My first approach did not work,” instead of, “I am not good enough to build a business.” One statement identifies a problem that can be addressed. The other turns a business challenge into a personal limitation.

How Ego Affects Decision-Making

Ego often enters business decisions quietly. It may appear as the need to be right, reluctance to admit a mistake, or the desire to appear successful even when the business is struggling.

A founder might avoid sharing disappointing sales figures with an advisor because doing so feels embarrassing. Another might refuse to adjust pricing because a lower price feels like an admission that the original offer was overvalued. Someone else may hire too quickly to look like a growing company, despite not having enough predictable revenue to support the expense.

These decisions have something in common: they prioritize how the founder feels or appears over what the business needs.

The sunk cost fallacy can make this even harder. When founders have invested substantial time and money into a product, they may feel compelled to continue simply because stopping would make the earlier investment seem wasted. But past costs cannot be recovered by spending more. The relevant question is whether another investment makes sense given what you know today.

Before making a significant decision, pause and ask yourself: If I were evaluating this opportunity for the first time today, knowing what I know now, would I still choose this path?

The answer may not automatically mean stopping. It may mean continuing with greater focus, testing a different approach, or setting a clear limit on future investment. The point is to make the decision based on present evidence rather than the emotional need to justify the past.

Learning From Rejection Without Taking It Personally

Rejection is part of building a startup. Prospective customers will decline offers, investors will pass on pitches, potential partners will choose other opportunities, and candidates may reject job offers. These experiences can be discouraging, particularly when a founder has limited external evidence that the business is on the right track.

The danger is interpreting rejection too broadly. One customer who dislikes your product does not prove that nobody wants it. One investor who declines to participate does not establish that your company is un-investable. At the same time, repeated rejection from the same customer segment should not be dismissed as bad luck.

The goal is to understand what the rejection reveals.

When a prospect declines, consider asking a respectful follow-up question: “Would you be willing to share what kept this from being the right fit?” The answer may reveal that the problem is not urgent enough, the price is too high, the buying process is too complicated, or the customer does not understand the value. Each possibility points toward a different next step.

The U.S. Small Business Administration’s market research guidance recommends using research to understand customer demand and market conditions. Customer interviews, surveys, and competitive analysis can help founders distinguish between an isolated rejection and a broader market problem.

Rejection becomes more useful when you treat it as information to investigate rather than a judgment to absorb.

Knowing When Persistence Becomes Denial

Entrepreneurs are frequently told to never give up. Persistence is important, but persistence without evaluation can become expensive denial.

A founder should continue pursuing a goal when there is a credible reason to believe the effort can produce a worthwhile result. That reason might be encouraging customer behavior, a clear improvement in conversion rates, strong retention, or a promising new market segment. Persistence is less defensible when the only argument for continuing is that the founder has already worked so hard.

There is no universal number of failed sales calls, months without revenue, or product revisions that tells every founder when to stop. The appropriate threshold depends on the business model, available cash, sales cycle, customer behavior, and consequences of continued investment.

What matters is deciding in advance what evidence you need.

For example, a founder might set a 90-day test to determine whether a new service offering has commercial potential. During that period, the founder could track qualified sales conversations, proposals, paid customers, and customer feedback. At the end, the founder reviews the evidence against the original expectations and decides whether to continue, change the offer, or stop the experiment.

This approach does not eliminate uncertainty. It prevents uncertainty from becoming an excuse for endless investment.

Creating Objective Decision Criteria

When your identity is closely tied to your startup, it helps to create a decision-making process that does not depend entirely on how you feel in the moment.

Start by identifying the business question. Are you deciding whether to launch a product, hire an employee, change pricing, pursue a new market, or discontinue an offering? Then write down the assumptions behind your preferred decision and identify what evidence would support or challenge them.

Next, choose measurable criteria that fit the decision. For a product launch, those criteria might include the number of customers willing to pay, the cost of acquiring a customer, repeat usage, or the time required to deliver the service. For a hiring decision, they might include available cash, workload, expected revenue, and the cost of delaying the hire.

Finally, set a review date. This prevents you from changing the rules whenever the results become uncomfortable.

A simple decision journal can help. Record what you decided, why you decided it, what you expected to happen, and when you will review the outcome. Later, compare your expectations with reality. You will begin to identify recurring patterns, including situations where fear makes you overly cautious or optimism causes you to underestimate risk.

Objective criteria are not a replacement for judgment. They provide a framework that helps you exercise judgment more consistently.

How to Receive Criticism From Customers, Advisors, and Employees

As your startup grows, feedback will come from people with different perspectives and different levels of understanding. Customers may focus on usability or price. Advisors may challenge your strategy. Employees may question priorities or explain why a process is not working.

Your job is not to agree with every criticism. It is to create enough space to understand it before deciding what to do with it.

Start by listening without immediately defending your choices. Ask for a specific example, clarify the concern, and look for the underlying issue. If a customer says your service is too complicated, find out which part creates difficulty. If an employee says priorities keep changing, ask how those changes affect their work. If an advisor questions your growth strategy, ask which assumptions they believe need stronger evidence.

Then separate the feedback from the person delivering it. Someone can communicate a valid concern poorly, just as someone you respect can offer advice that does not fit your situation. Evaluate the substance rather than automatically accepting or rejecting the message.

Founders also need to make criticism safe for their teams to share. If employees learn that disagreement leads to defensiveness or punishment, they will eventually stop raising concerns. That deprives the business of information it needs to improve.

The Lean Startup discussion of psychological safety and team performance highlights the importance of creating conditions in which people can collaborate, take ownership, and learn together.

A useful leadership habit is to thank people for raising concerns, investigate the facts, and explain what you decide to do. You do not have to implement every suggestion. You do need to demonstrate that honest feedback receives serious consideration.

Building Founder Resilience: Turning Setbacks Into Information

Founder resilience is not the ability to remain positive all the time. It is the ability to experience disappointment, recover your perspective, and take constructive action without allowing a difficult outcome to define you.

That distinction matters because startups rarely follow a straight line. A product launch may underperform. A promising partnership may fall apart. A reliable customer may leave. Cash flow may tighten just as you believe the business is gaining momentum.

Resilient founders acknowledge the disappointment without allowing it to become the entire story. They also recognize when a problem requires practical action rather than more positive thinking.

An article from Kevin Martin (a GrowthCraft Advisor) of Positive Effects Coaching & Hypnosis explores how fear, self-doubt, and habitual thought patterns can affect business owners’ behavior. Its emphasis on recognizing internal reactions offers a useful complement to practical startup disciplines: understanding your emotional response can help you avoid letting that response dictate your next business decision.

For a first-time founder, resilience can be developed through a few consistent practices. Maintain relationships outside your company so that your sense of belonging does not depend entirely on business performance. Make time to reflect on what you learned from difficult experiences. Seek honest feedback from people who can challenge you without diminishing you. And recognize progress in the quality of your decisions, not just in revenue or growth.

Most importantly, remember that you can take responsibility for a business outcome without turning it into a judgment of your personal worth.

When a setback occurs, ask yourself three questions: What happened? What can I learn from it? What will I do differently next time?

These questions redirect your attention from self-criticism toward improvement.

How GrowthCraft Can Help Founders Develop a Healthier Mindset

Developing the right mindset is important, but founders should not have to figure everything out alone. Early-stage entrepreneurship often involves making consequential decisions without the experience, resources, or support systems available to leaders in established companies.

GrowthCraft helps first-time and early-stage founders work through the practical challenges of building a business, including market fit, business growth, financial structure, and legal protection. Its educational resources, founder community, expert support, Office Hours, and mastermind groups can give entrepreneurs opportunities to test assumptions, learn from peers, and receive perspectives beyond their own.

Mastermind groups are particularly valuable for founders who have become too close to a decision. Other entrepreneurs can ask the questions you may be avoiding, share lessons from similar experiences, and help you distinguish a genuine business problem from an emotional reaction. Accountability also makes it easier to follow through on decisions and review the results honestly.

The goal is not to remove the uncertainty that comes with entrepreneurship. It is to help you navigate that uncertainty with better information, stronger decision-making habits, and support from people who understand the challenges of building a company.

A founder who can admit uncertainty, accept feedback, and change direction when the evidence calls for it is not demonstrating weakness. That founder is developing the judgment required to lead.

Final Thought: Build the Business Without Losing Yourself

Your startup will challenge your assumptions, test your patience, and occasionally make you question your decisions. That is part of entrepreneurship, not proof that you are failing as a person.

The strongest founders are not necessarily those who never make mistakes or never experience self-doubt. They are the ones who remain willing to examine their assumptions, learn from uncomfortable information, and change course when necessary.

You can believe in yourself without believing every idea you have is right. You can be persistent without being stubborn. And you can take a business setback seriously without taking it as a personal verdict.

Your startup deserves thoughtful leadership. You deserve an identity that is bigger than your startup.

Learn to separate the two, and you give yourself a better chance of building a business that succeeds without requiring you to prove your worth through every decision.

Frequently Asked Questions

1. Why is it important to separate your identity from your startup?

Separating your identity from your startup helps you evaluate business outcomes objectively. When your self-worth depends on the company’s performance, criticism and setbacks can trigger defensive reactions or poor decisions. Recognizing that your business is something you build, rather than a measure of your personal value, makes it easier to learn, adapt, and lead effectively.

2. How can founders stop taking customer rejection personally?

Treat rejection as feedback about a particular offer, customer, price, or situation rather than as a judgment of your abilities. Ask respectful follow-up questions, look for recurring patterns, and compare feedback with actual customer behavior. One rejection may reveal little, while a consistent pattern across qualified prospects may indicate that your business approach needs to change.

3. How do you know when to pivot a startup instead of persisting?

Consider a pivot when repeated experiments and customer evidence challenge important assumptions behind your current approach. Before making the decision, establish measurable criteria, such as customer demand, willingness to pay, retention, or sales conversion. Persistence makes sense when evidence supports continued investment. A pivot may be necessary when the current approach consistently fails to produce the results needed for a sustainable business.

4. What is the sunk cost fallacy in entrepreneurship?

The sunk cost fallacy occurs when founders continue investing in a project because they have already spent substantial time, money, or effort on it. Previous investment cannot be recovered simply by continuing. A better decision considers future costs, potential benefits, available alternatives, and the evidence currently available.

5. How can first-time founders develop a more resilient entrepreneurial mindset?

Founders can build resilience by reflecting on setbacks, maintaining relationships outside the business, seeking constructive feedback, and setting objective decision criteria. Keeping a decision journal and participating in founder communities or mastermind groups can also help. The goal is to learn from difficult experiences without allowing them to define your identity or determine your next move automatically.

References and Further Reading

  1. Positive Effects Coaching & Hypnosis: Entrepreneur Mindset Guide for Lasting Growth. Explores how fear, self-doubt, and habitual thinking can influence entrepreneurial behavior.
  2. Positive Effects Coaching & Hypnosis: What a Business Mindset Coach Can Do for You. Discusses mindset challenges, emotional responses, and decision-making under pressure.
  3. The Lean Startup: Principles. Explains validated learning and the build-measure-learn approach to testing business assumptions.
  4. U.S. Small Business Administration: Market Research and Competitive Analysis. Provides practical guidance on evaluating customer demand and market opportunities.
  5. Psychology Today: Should You Quit or Push Through? How to Decide With Clarity. Explores persistence, the sunk cost fallacy, and deciding when to change direction.
  6. Harvard Business Review: “Create Something and Start Selling It”. Discusses startup strategy, early customer feedback, and iterative development.
Your Startup Is Not Your Identity: Developing the Mindset to Make Better Business Decisions Read More »

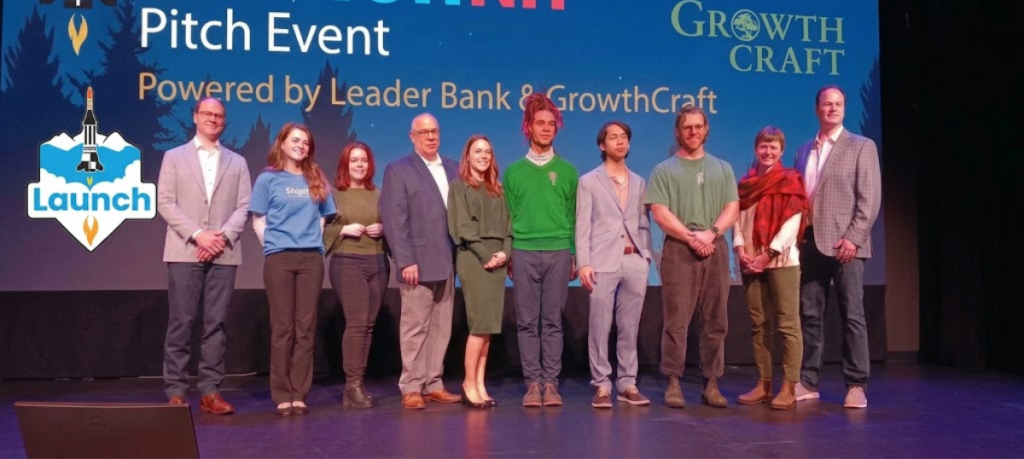
2026 Launch NH Pitch Event powered by Leader Bank and GrowthCraft, celebrating startup finalists FIRST Communities, GyroGel, SkipItTech Inc., and New Hampshire entrepreneurs.

Celebrating New Hampshire Innovation: Thank You to Launch NH, Leader Bank, GrowthCraft, and the 2026 Pitch Finalists

2026 Launch NH Pitch Event powered by Leader Bank and GrowthCraft, celebrating startup finalists FIRST Communities, GyroGel, SkipItTech Inc., and New Hampshire entrepreneurs.
Celebrating New Hampshire innovation at the 2026 Launch NH Pitch Event, powered by Leader Bank and GrowthCraft, with congratulations to all 10 finalists and top-three winners FIRST Communities, GyroGel, and SkipItTech Inc.

Celebrating New Hampshire Innovation: Thank You to Launch NH, Leader Bank, GrowthCraft, and the 2026 Pitch Finalists

New Hampshire’s startup community continues to grow, and the 2026 Launch NH Pitch Event was another opportunity to celebrate the founders, ideas, and entrepreneurial spirit helping move that growth forward.

On October 13, 2026, entrepreneurs, investors, mentors, and members of the startup community gathered at BNH Stage in Concord, New Hampshire, for the 2026 Launch NH Pitch Event, powered by Leader Bank and GrowthCraft.

The event brought together 10 promising startups to present their businesses, demonstrate their ideas, share their funding needs, and receive feedback from the entrepreneurial and investment community. More than a pitch competition, it was an opportunity to connect founders with the people, resources, and relationships that can help turn promising ideas into successful businesses.

Congratulations to all 10 finalists, with special recognition for our top three winners: FIRST Communities, GyroGel, and SkipItTech Inc.

Thank You to the Organizations Making It Possible

A successful startup ecosystem does not happen by accident. It takes organizations willing to invest their time, resources, experience, and relationships in the next generation of entrepreneurs.

Thank You, Launch NH

Launch NH deserves tremendous credit for creating opportunities for New Hampshire entrepreneurs to showcase their businesses, connect with potential investors, and receive valuable feedback.

Pitch events give founders something especially important during the early stages of building a company: the opportunity to explain their vision, test their message, answer difficult questions, and learn from people who understand the challenges of growing a business.

By bringing founders and the broader entrepreneurial community together, Launch NH continues to help strengthen New Hampshire’s innovation ecosystem.

Learn more at Launch NH.

Thank You, Leader Bank

Thank you to Leader Bank for supporting the event and helping connect emerging companies with potential investors and business leaders.

Access to capital is an important part of building a company, but relationships matter just as much. Connecting founders with investors who understand their markets and ambitions can help create opportunities that extend well beyond a single pitch.

Leader Bank’s involvement helps extend the value of the competition beyond the event itself, creating opportunities for founders to develop relationships with potential supporters and investors.

Thank You, GrowthCraft

GrowthCraft is proud to support early-stage founders as they navigate the difficult work of building a business.

A compelling idea is an important starting point, but successful entrepreneurship requires much more. Founders must validate their markets, understand their customers, develop sound financial plans, establish effective operations, protect their businesses, and create a practical roadmap for growth.

Through its founder community, educational workshops, advisor support, peer masterminds, and accountability resources, GrowthCraft helps entrepreneurs make progress on these challenges.

We believe founders should have access to practical guidance and a supportive community without necessarily giving up equity or committing to a traditional accelerator program.

Supporting the Launch NH Pitch Event is one way GrowthCraft contributes to a stronger entrepreneurial ecosystem, where founders can learn from one another, develop their businesses, and build relationships that continue long after the presentations end.

Learn more at GrowthCraft.org.

Congratulations to the Top Three Winners

Every finalist deserves recognition for stepping forward, presenting an idea, and putting their work in front of an audience. This year’s top three companies stood out in the competition.

1. FIRST Communities

Founder: Jamie

Congratulations to Jamie and FIRST Communities for earning a place among the competition’s top three winners.

The company represents one of the entrepreneurial teams working to develop an idea into a business with the potential to serve a market need. The pitch event provided an opportunity to introduce its vision, receive feedback, and build connections that may help support its next stage of development.

We look forward to seeing how Jamie and the FIRST Communities team continue to develop the business and pursue their goals.

2. GyroGel

Founder: Peter

GyroGel is developing an innovative approach to jawbone and facial reconstruction. Its technology combines 3D-printed bioceramics with a biodegradable gel-based material designed to support natural bone regrowth. The goal is to improve reconstructive options for patients, including those who require jaw reconstruction following cancer treatment.

The company’s work illustrates how research and engineering can lead to new approaches to important medical challenges. Moving innovations like this from research into clinical use requires continued development, validation, and collaboration across scientific, medical, and business communities.

Congratulations to Peter and the GyroGel team on their top-three finish and their continued work advancing this promising technology.

Learn more at www.gyrogel.com.

3. SkipItTech Inc.

Founder: Emily

Congratulations to Emily and SkipItTech Inc. for earning a top-three position.

The Launch NH Pitch Event offered SkipItTech an opportunity to present its business, communicate its value proposition, and connect with people who may help the company move forward.

For an early-stage company, recognition in a pitch competition can be an important milestone. It can help build visibility, open conversations with potential partners and investors, and provide momentum as the team works to develop and grow its business.

We congratulate Emily and the SkipItTech team and look forward to following their progress.

Learn more at www.skipit.tech.

Recognizing All 10 Finalists

The strength of a pitch competition is not measured only by its winners. Every participating company brings a different perspective, a different problem to solve, and a different entrepreneurial journey.

We congratulate all 10 finalists for sharing their work and contributing to this year’s event.

Comprehension Clicker

Founder: Jetrin

Comprehension Clicker is an education technology startup developing a handheld classroom feedback device. Students can signal how well they understand a lesson in real time, giving instructors a better sense of when students need additional explanation or support. Its approach aims to make classroom feedback more immediate and accessible.

Congratulations to Jetrin for bringing this concept to the competition and contributing to the conversation about how technology can support teaching and learning.

Learn more at www.comprehensionclicker.com.

SoCitty

Founder: Holly

SoCitty joined the finalist group with its entrepreneurial vision and the opportunity to introduce its concept to the New Hampshire startup community.

Pitching provides founders with an opportunity to communicate their ideas, receive feedback, and make connections that can help inform the next stage of development.

Congratulations to Holly and the SoCitty team for being among this year’s finalists.

Learn more at www.socitty.ai.

BasiFly

Founder: Mike

BasiFly joined the finalist lineup, contributing another entrepreneurial perspective to a competition designed to showcase emerging companies and help founders connect with potential supporters.

Congratulations to Mike and the BasiFly team for presenting their business and participating in this year’s event.

Learn more at www.basifly.com.

Enabled Therapeutics

Founder: Brett

Enabled Therapeutics was among the 10 finalists presenting its venture. Its participation highlighted the range of ideas and opportunities represented by founders working to bring new solutions to market.

Congratulations to Brett and the Enabled Therapeutics team for sharing their vision and earning a place among this year’s finalists.

Learn more at www.enabledtherapeutics.com.

FlexiGrace Bio

Founder: Arun

FlexiGrace Bio brought its entrepreneurial vision to the finalist group. As with other early-stage ventures, the opportunity to present its concept and connect with experienced business leaders can help inform its next steps.

Congratulations to Arun and the FlexiGrace Bio team for participating in the competition and contributing to New Hampshire’s growing startup community.

Contact: www.flexigrace.bio

Correct’em Corporation

Founders: Rachel and Roy

Correct’em Corporation was one of the 10 startups selected to pitch. The event gave the company an opportunity to share its business proposition, receive feedback, and build relationships within the startup and investment communities.

Congratulations to Rachel and Roy for bringing Correct’em Corporation to the Launch NH Pitch Event and sharing their entrepreneurial vision.

Learn more at www.correctemcorp.com.

ACATbio

Founders: Jennifer and Taylor

ACATbio was among the 10 finalists selected to present at the 2026 Launch NH Pitch Event. The competition gave the team an opportunity to introduce its business, share its vision, and connect with members of the startup and investment communities.

Congratulations to Jennifer and Taylor for bringing ACATbio to the competition and contributing to New Hampshire’s growing entrepreneurial ecosystem.

Learn more at www.acatbio.com.

Why Events Like This Matter for Startups

Building a company can be an isolating experience, especially for first-time founders. Entrepreneurs often have to make important decisions about their products, customers, finances, and growth plans while working with limited resources and incomplete information.

Events like the Launch NH Pitch Event help address that challenge by bringing founders into a room with people who can offer different perspectives, ask important questions, and open doors to new opportunities.

A pitch competition also provides a valuable learning experience. Preparing a short presentation forces founders to clarify what problem they solve, who needs their solution, why their approach matters, and what they need to accomplish next.

The questions that follow can be just as valuable as the pitch itself. Feedback may reveal assumptions that need testing, customer segments that deserve more attention, or business milestones that need to be established before pursuing investment.

And while winning is certainly worth celebrating, every founder can leave an event like this with new contacts, new insights, and a clearer understanding of the work ahead.

For early-stage companies, that progress matters.

Helping Founders Turn Ideas Into Businesses

At GrowthCraft, we believe entrepreneurship should not be a journey founders have to navigate alone.

Founders need more than an innovative product or a persuasive pitch deck. They need a practical plan for moving forward, a way to prioritize their limited time and resources, and access to people who can help them work through unfamiliar challenges.

That is why GrowthCraft focuses on helping early-stage founders develop the core elements of a sustainable business, including market validation, business growth, financial structure, and legal protection.

We are pleased to support an event that brings these founders into the spotlight and helps connect them with the broader entrepreneurial community.

Congratulations again to Jamie and FIRST Communities, Peter and GyroGel, and Emily and SkipItTech Inc. on their top-three finishes. And congratulations to Jetrin, Holly, Mike, Brett, Arun, Rachel, Roy, and Danny for sharing their entrepreneurial journeys with the community.

Most importantly, thank you to Launch NH and Leader Bank for helping make this event possible, and to all 10 finalists for contributing their ideas, energy, and ambition.

The next successful company may begin with a conversation, a new connection, or a piece of feedback received at an event like this. We look forward to seeing what these founders build next.

Here’s to the founders who keep building, the organizations that support them, and a stronger future for entrepreneurship in New Hampshire.

Celebrating New Hampshire Innovation: Thank You to Launch NH, Leader Bank, GrowthCraft, and the 2026 Pitch Finalists Read More »

Early-stage startup founders reviewing financial projections and funding-readiness metrics before meeting with investors

How to Know If Your Startup Is Actually Ready to Raise Money

How to Know If Your Startup Is Actually Ready to Raise Money

Early-stage startup founders reviewing financial projections and funding-readiness metrics before meeting with investors
Before raising capital, founders should understand their customers, market, financials, business model, and the specific milestones funding will help achieve.

How to Know If Your Startup Is Actually Ready to Raise Money

Raising money can feel like the next obvious step for a startup. You have an idea, you have built something, you may have early customers, and now you need capital to move faster.

But needing money and being ready to raise money are not the same thing.

For an early-stage founder, one of the most important funding decisions is knowing whether outside capital will actually help the company reach its next meaningful milestone. Investors are not simply looking for startups that need cash. They are looking for evidence that additional capital can help a promising business become more valuable.

That distinction is at the heart of funding readiness.

The U.S. Securities and Exchange Commission specifically recommends that companies consider their capitalization table, financials, funding requirements, use of proceeds, investor strategy, advisors, and long-term vision before beginning a capital raise. The Small Business Administration similarly points to market research, financial projections, management capability, and due diligence as important parts of preparing for outside funding.

For first-time founders, the better question is not, “How do I raise money?”

It is, “What would make an investor believe that putting money into my company today is likely to produce a meaningful result tomorrow?”

Funding Is a Tool, Not the Goal

One of the easiest mistakes for a startup founder to make is treating fundraising as a milestone in itself.

Raising $500,000 does not mean the startup is successful. Raising $2 million does not mean the business has found product-market fit. Funding simply gives the company additional resources.

The real purpose of funding should be tied to a specific business outcome.

Perhaps you need capital to finish development of a product, hire the people required to deliver it, conduct a larger market test, expand customer acquisition, complete regulatory work, or reach a revenue milestone. Whatever the reason, you should be able to explain what the money will accomplish.

The SEC recommends that founders calculate their runway and have a clear plan for how the proceeds will be used.

A useful test is this:

If an investor gave you the money tomorrow, what would be measurably different about your company 12 to 18 months from now?

If you cannot answer that question, you may not be ready to raise.

Why Raising Money Too Early Can Hurt a Startup

More money does not automatically solve startup problems.

In fact, raising money before you understand your customer, business model, or market can make existing problems more expensive.

Suppose you raise $1 million before you know exactly who your best customer is. You now have money to hire employees, build features, spend on marketing, and increase operating expenses. But if the underlying customer assumptions are wrong, you can spend $1 million discovering what you could have learned for $50,000.

Early funding can also create pressure to grow before the company is ready. Investors expect progress. Employees are hired. Expenses increase. Expectations change. The founder can end up managing a larger organization before the basic business has been validated.

This does not mean founders should always wait until they are profitable or have significant revenue. Some startups need capital very early because they have substantial research, development, regulatory, manufacturing, or infrastructure requirements.

The question is whether you have enough evidence to justify the amount of capital you are seeking and whether the capital has a clearly defined job.

The Questions Investors Will Ask

You should be able to answer the basic investor questions before you start pitching.

Y Combinator’s seed fundraising guidance provides a useful framework that includes the problem, customer, solution, market, competition, traction, business model, team, and fundraising requirements.

Those questions generally come down to five areas:

  • Why this problem? Can you demonstrate that the problem is real, important, and painful enough for customers to address?
  • Why this solution? What have you built, and why is it meaningfully better, faster, cheaper, easier, or more valuable than existing alternatives?
  • Why this market? How large is the opportunity, and what evidence supports your market assumptions?
  • Why your company? Why are you and your team particularly qualified to solve this problem?
  • Why now and why funding? What has changed, what have you learned, and what will additional capital allow you to accomplish?

You do not need to have perfect answers. Early-stage companies rarely do. You do need to understand what you know, what you do not know, and what evidence supports your assumptions.

Evidence of Customer Demand

Customer demand is one of the strongest indicators of funding readiness.

That does not necessarily mean you need millions of dollars in revenue. Depending on the stage and type of company, useful evidence could include paying customers, signed contracts, pilot customers, repeat usage, preorders, strong customer retention, partnerships, letters of intent, or measurable engagement.

The important distinction is between what people say and what people do.

Someone telling you, “That’s a great idea,” is encouraging.

Someone agreeing to pay for it is much stronger evidence.

Techstars similarly emphasizes traction and evidence that customers want the product as important elements of a compelling investment case.

Before approaching investors, ask yourself:

  • Who has actually used the product?
  • Who has paid for it?
  • Who has used it more than once?
  • What percentage of customers continue using it?
  • What problem caused them to buy?
  • Why did customers choose you instead of an alternative?
  • What have customers asked you to improve?

Your answers create a much stronger story than a collection of assumptions.

Business Model Clarity

Investors need to understand how the company eventually makes money.

Your business model does not have to be perfect. It does need to be understandable.

Can you explain who pays, what they pay for, how much they pay, how frequently they pay, and what it costs you to deliver the product or service?

If your current model is expected to change, explain why.

A founder who says, “We haven’t figured out monetization yet,” may be describing a legitimate early-stage reality. But the founder should also be able to explain what has been tested and what needs to be learned next.

A strong early business model conversation might sound like this:

“We currently charge X for Y. We tested three pricing approaches with 20 customers. This option produced the strongest conversion and retention. We believe we can improve gross margins as volume increases.”

That demonstrates learning rather than pretending certainty.

Financial Understanding

You do not need to be an accountant to raise money.

You do need to understand your company’s financial reality.

At minimum, you should know your current cash balance, monthly expenses, cash burn, runway, revenue, gross margin if applicable, major cost categories, and the assumptions behind your financial projections.

You should also know exactly how much you are asking for and why.

The SEC specifically identifies financial statements, capitalization tables, runway, and a clear plan for the use of proceeds as important components of capital-raising preparation.

Your financial model should not exist simply because an investor expects to see a spreadsheet. It should help you make decisions.

For example, if you are raising $750,000, what does that money allow you to accomplish that $300,000 would not? What happens if you raise $1 million? What happens if you raise only $500,000?

Understanding these scenarios makes you a better capital allocator and a more credible founder.

The U.S. Small Business Administration’s business planning guidance (https://www.sba.gov/counseling/plan-your-business/) also recommends connecting funding requirements with financial projections and explaining the assumptions behind those projections.

Market Opportunity

A great product in a tiny or shrinking market may not produce the type of return some investors are looking for.

That does not mean every startup needs to claim a massive market. It means you need to understand the market you are entering.

Start with the actual customer.

How many potential customers exist? What do they currently spend to solve the problem? What alternatives are available? How competitive is the market? What trends could increase or decrease demand?

The SBA recommends examining demand, market size, pricing, competition, customer characteristics, and broader economic factors when conducting market research.

Be careful with the common “1% of a $10 billion market” argument. Investors generally need more than a large theoretical market number. They need to understand how your company can realistically capture a meaningful portion of that opportunity.

Founder and Team Readiness

At the earliest stages, investors are investing heavily in the people.

That does not mean you need a large team.

It means the people involved need to make sense for the company’s current stage and future challenges.

Who owns the technical work? Who understands customers? Who handles operations? Who is responsible for sales? What capabilities are missing?

If there is a major gap, acknowledge it.

A founder who understands the company’s weaknesses is often more credible than one who claims the team can do everything.

Research discussed in Harvard Business Review also highlights the importance investors place on startup teams during due diligence, alongside business model, market opportunity, and growth plans.

Legal and IP Considerations

Legal preparation is easy to overlook when you are focused on building the product.

It can become a serious problem during due diligence.

Before raising capital, you should know who owns the company, how equity is divided, whether founder agreements are documented, whether intellectual property belongs to the company, and whether important contracts are in place.

If contractors or employees created important technology, make sure the company has appropriate agreements addressing intellectual property ownership.

If your company relies on patents, trademarks, copyrights, proprietary technology, trade secrets, or other intellectual property, understand what has been protected and what remains exposed.

The SBA specifically identifies intellectual property plans, patents, legal documents, licenses, permits, contracts, and other supporting materials as information that may belong in a company’s funding documentation.

The SEC also recommends having experienced legal and accounting advisors involved in the capital-raising process.

This is an area where professional legal advice is particularly important. Securities laws can apply when a company sells equity or other securities, and the appropriate exemption and compliance requirements depend on the circumstances. The SEC provides current educational resources on exempt offerings and capital raising.

What Should Be Prepared Before Approaching Investors?

You do not need a giant data room before having your first investor conversation. You should, however, be prepared to support the story you are telling.

At a minimum, consider preparing:

A clear pitch deck. It should explain the problem, customer, solution, market, traction, business model, team, competitive landscape, and funding request. Y Combinator’s seed fundraising framework provides a useful starting structure.

A financial model. Your model should show historical performance where available, projected revenue and expenses, cash requirements, and the assumptions behind your projections.

A capitalization table. Know exactly who owns what before inviting new investors into the company.

Customer evidence. Organize your strongest evidence of demand, including revenue, customer growth, retention, pilots, contracts, partnerships, testimonials, or other meaningful indicators.

A use-of-funds plan. Explain where the money will go and what business milestones those expenditures are intended to produce.

A due diligence folder. Organize important corporate, financial, legal, intellectual property, customer, employee, and contractual documents so you can respond efficiently when investors begin asking questions.

The SBA describes due diligence as a process in which investors may examine management, markets, products and services, corporate governance documents, and financial statements.

A Practical Funding-Readiness Checklist

Before actively raising money, give yourself one point for every statement you can confidently answer “yes” to:

1. I can clearly explain the customer problem. I can identify the specific customer experiencing it and explain why the problem matters.

2. I have evidence that customers want the solution. I have more than opinions or survey responses. I have meaningful evidence such as usage, revenue, pilots, contracts, or other customer behavior.

3. I understand my business model. I know who pays, what they pay for, how much they pay, and how the economics are expected to work.

4. I understand my numbers. I know my cash position, burn rate, runway, revenue, major expenses, and key financial assumptions.

5. I understand my market. I can explain my target market, competitors, customer alternatives, market size, and why the opportunity can grow.

6. I know what the funding will accomplish. I can connect the amount I am raising to specific milestones rather than simply saying I need money to grow.

7. My team can execute the next stage. I know the team’s strengths and the important capabilities we still need.

8. My ownership and legal structure are organized. My cap table, corporate records, founder agreements, contracts, and IP ownership are reasonably prepared.

9. I know which investors I should approach. I am targeting investors whose stage, industry interests, geography, check size, and expertise fit my company.

10. I can explain what happens if I do not raise. I understand my alternatives and what the company can accomplish with its existing resources.

If you cannot check most of these boxes, that does not mean your startup is failing.

It means you have identified the work that should happen before the fundraising process becomes the primary focus.

GrowthCraft’s Role in Funding Readiness

This is where funding readiness fits into the broader work GrowthCraft provides for early-stage, first-time founders.

GrowthCraft’s approach is not simply about helping a founder create a pitch deck and start asking investors for money. The more important question is whether the company is ready for the scrutiny that comes with outside capital.

That means looking at the business as a whole: the customer and market, business model, financial structure, legal protection, operating priorities, and founder decision-making.

GrowthCraft can serve as a resource for founders working through those questions before they begin a serious fundraising process. The goal is not to make every startup investor-ready immediately. The goal is to help founders understand what needs to be true before outside capital is likely to create meaningful value.

Sometimes the right answer is to raise money now.

Sometimes the right answer is to spend the next six months proving customer demand, refining the business model, cleaning up the financials, protecting intellectual property, or reaching a specific operating milestone first.

Knowing the difference is part of being ready.

Final Thought: Raise Money Because You Are Ready to Use It

The strongest reason to raise startup funding is not that your bank account is getting low.

It is that you have learned enough about your business to know what additional capital can accomplish.

You understand the customer. You have evidence of demand. You know how the business can make money. You understand the market. You know your numbers. Your team is capable of executing the next stage. Your legal and ownership structure can withstand due diligence. Most importantly, you have a specific reason that additional capital should make the company substantially stronger.

Fundraising is not a substitute for figuring out the business.

It is a tool for accelerating a business that is beginning to demonstrate that it works.

For an early-stage founder, that distinction can save time, money, ownership, and a great deal of frustration.

Frequently Asked Questions

How much revenue does a startup need before raising money?

There is no universal revenue threshold for raising startup funding. Some startups raise before generating revenue because they require substantial development, research, regulatory work, or other upfront investment. The more important question is whether you have credible evidence supporting your assumptions and a clear reason why additional capital is needed now.

Should I raise money before I have product-market fit?

Sometimes. Early-stage investors may fund companies before product-market fit if the opportunity, team, technology, market, and early evidence are compelling. However, raising substantial capital before understanding your customer can increase the cost of experimentation. Founders should be clear about what they have validated and what they still need to learn.

What financial information do investors expect?

Investors will typically want to understand your current financial position, ownership structure, revenue and expenses where applicable, cash burn, runway, financial projections, and how you intend to use the funding. The SEC specifically identifies financial statements, capitalization tables, runway calculations, and use-of-proceeds plans as important capital-raising preparation.

Do I need a pitch deck before talking to investors?

A formal pitch deck is not necessarily required for every early conversation, but you should be able to clearly explain your problem, customer, solution, market, traction, business model, team, and funding requirements. Once you begin a formal fundraising process, a well-structured deck becomes an important communication tool.

What should I do if my startup is not ready to raise money?

Turn the gaps into milestones. If customer demand is weak, focus on customer validation. If the business model is unclear, test pricing and purchasing behavior. If the financial model is weak, build a realistic cash-flow forecast. If your legal or IP structure is incomplete, address it before due diligence. Being “not ready” is useful information when you know exactly what needs to change.

Recommended Source Materials

For readers who want to go deeper, these are strong reference resources:

How to Know If Your Startup Is Actually Ready to Raise Money Read More »

Photograph showing a woman studying in a bright coworking office beside a window, using a laptop and writing in an open notebook. Desk includes coffee, smartphone, pen, and potted plants, while background workers and modern furnishings convey a collaborative workspace. Startup founder reviewing business goals and progress at a desk.

Why Most Startup Goals Fail Before the Work Even Begins

Why Most Startup Goals Fail Before the Work Even Begins

Photograph showing a woman studying in a bright coworking office beside a window, using a laptop and writing in an open notebook. Desk includes coffee, smartphone, pen, and potted plants, while background workers and modern furnishings convey a collaborative workspace. Startup founder reviewing business goals and progress at a desk.
Successful startup goals begin with clear priorities, measurable outcomes, and a plan for execution.

How first-time founders can set meaningful goals, establish accountability, and turn ambitious plans into measurable progress.

A startup can have a great idea, a talented founding team, and a clear vision of where it wants to go, yet still struggle to make meaningful progress. Often, the problem isn’t a lack of effort. It’s that the goals guiding the business were never designed to succeed in the first place.

Many first-time founders begin with ambitious objectives: acquire 100 customers, launch a product, generate $500,000 in revenue, or become a recognized name in their industry. These are worthwhile ambitions, but without a clear plan, measurable milestones, and someone responsible for execution, they remain wishes rather than working business goals.

The challenge is particularly significant for early-stage startups. Founders are often responsible for everything, from product development and customer discovery to marketing, finances, and daily operations. With so many demands competing for attention, even well-intentioned goals can quickly lose momentum.

The solution isn’t necessarily to work harder or create a more complicated business plan. It’s to establish a practical system that connects what the startup wants to accomplish with the work required to get there.

Understanding why startup goals fail is the first step toward building that system. By making goals specific, limiting priorities, measuring outcomes, assigning ownership, and reviewing progress regularly, founders can create a more reliable path from planning to execution.

1. The Problem With Vague Startup Goals

One of the most common mistakes first-time founders make is confusing a general business ambition with an actionable goal.

Consider a founder who says, “We need to improve our marketing.” While this may accurately describe a business problem, it doesn’t tell anyone what needs to happen, how success will be measured, or when the work should be completed.

Should the company publish more content? Improve its website? Conduct customer interviews? Launch an advertising campaign? Without a specific objective, the founder and team may pursue several unrelated activities without knowing whether any of them are producing results.

A useful startup goal should describe a desired outcome, establish a measurable target, and include a timeframe. For example, instead of saying, “Improve marketing,” a founder might set a goal to generate 20 qualified sales leads per month by the end of the next quarter.

That goal gives the team something concrete to work toward. It also creates an opportunity to evaluate whether the chosen marketing activities are effective.

The Objectives and Key Results (OKRs) framework offers a useful way to think about this distinction. An objective describes what a team wants to accomplish, while key results define how it will measure success.

For a startup, the important lesson is that a goal should guide decisions, not simply describe an aspiration.

Before committing to a goal, founders should be able to answer three questions: What exactly are we trying to accomplish? How will we know when we have succeeded? When do we expect to achieve it?

If those questions are difficult to answer, the goal probably needs more work before execution begins.

2. Too Many Priorities Can Prevent Progress

Early-stage founders rarely have a shortage of ideas. They may want to launch new features, improve their website, find investors, hire employees, develop partnerships, and expand into new markets, all at the same time.

The problem is that every new priority competes for limited resources. A startup has only so much time, money, and management attention. Trying to accomplish too many things simultaneously can leave important projects unfinished.

This is especially challenging when the founder is also the person responsible for approving decisions, solving problems, and completing much of the work.

A practical approach is to identify the two or three most important business outcomes for the next 90 days. These should be the objectives that will make the greatest difference to the company’s immediate progress.

For example, an early-stage software startup might decide that its most important priorities are validating customer demand, improving product reliability, and establishing a repeatable customer onboarding process. Other worthwhile projects can wait until these objectives are addressed.

This doesn’t mean ignoring everything else. It means recognizing that not every good idea deserves immediate attention.

The principle of limiting work in progress, commonly used in Kanban and other workflow management approaches, is relevant here. When too many projects are active at once, teams spend more time switching between tasks and less time completing them.

Founders should regularly ask whether a proposed new priority supports an existing objective or distracts from it. If it doesn’t support the company’s most important goals, it may belong on a later planning list.

A startup doesn’t need to accomplish everything this quarter. It needs to accomplish the right things.

3. Activity Is Not the Same as Results

A busy startup can create the impression of progress without actually moving closer to its goals.

A founder might spend hours attending networking events, publishing social media posts, sending emails, and scheduling meetings. These activities may be useful, but they don’t automatically produce customers, revenue, or product validation.

The distinction between activity and outcomes is critical.

Activity measures the work being performed. Outcomes measure the results that work is intended to produce.

For example, a startup pursuing customer growth might track the number of sales calls completed each week. That’s a useful activity metric because it helps the founder understand whether enough outreach is taking place. However, the number of qualified prospects who agree to a demonstration or become paying customers is a more direct measure of business progress.

Both types of metrics have a purpose. Activity metrics help founders understand whether the work is happening. Outcome metrics help them determine whether the work is effective.

The What Matters resource on OKRs emphasizes the importance of measurable results rather than simply tracking completed tasks. This is a valuable distinction for founders who need to make decisions with limited time and resources.

A practical way to apply this principle is to connect every major activity to an intended result.

If the goal is to validate demand, conducting customer interviews is an activity. Identifying a consistent problem that customers are willing to pay to solve is a potential outcome.

If the goal is to improve customer retention, sending follow-up emails is an activity. Increasing the percentage of customers who continue using the product is an outcome.

Before starting a project, ask what business result it is supposed to produce. If that result cannot be clearly identified, reconsider whether the activity deserves priority.

4. Create Goals That Can Actually Be Measured

A goal without a measurement is difficult to manage. Founders need a way to determine whether they’re making progress, falling behind, or working toward an objective that may no longer be realistic.

The SMART framework is a familiar starting point. It encourages goals to be specific, measurable, achievable, relevant, and time-bound.

For an early-stage startup, the framework is most useful when it forces the founder to think through the details of execution.

Imagine a startup that wants to improve customer acquisition. “Get more customers” is too broad to guide daily decisions. A more useful goal might be to acquire 15 paying customers within 90 days, using customer interviews, targeted outreach, and product demonstrations.

The goal now has a clear target and deadline. The founder can break it into smaller milestones, such as identifying a defined group of potential customers, completing a certain number of discovery conversations, and evaluating how many prospects become paying customers.

However, founders should be careful not to confuse measurable with meaningful. A startup can easily measure website visits, social media followers, or the number of emails sent. Those figures only matter if they help explain progress toward an important business outcome.

Choose a small number of metrics that directly relate to the goal. For example, a startup working to improve its sales process might monitor qualified leads, demonstration-to-customer conversion, and the time it takes to close a sale.

The appropriate metrics will vary depending on the company’s stage and business model. An idea-stage startup may need to measure customer interviews and evidence of demand, while a startup with paying customers may need to focus on revenue, retention, and customer acquisition costs.

The goal is not to create an elaborate reporting system. It’s to establish a clear way to determine whether the work is producing the intended result.

5. Assign Someone Responsibility for Every Goal

Even a well-defined goal can fail when nobody is clearly responsible for making it happen.

In a small startup, founders often assume that everyone understands who is responsible for a particular project. Unfortunately, shared responsibility can easily become no responsibility at all.

A team might agree that improving customer onboarding is important, but if nobody owns the project, decisions can be delayed, problems can go unresolved, and deadlines can pass without meaningful progress.

Every major goal should have one clearly identified owner. That person is responsible for coordinating the work, monitoring progress, identifying obstacles, and communicating when the goal is at risk.

Ownership doesn’t mean that one person must do all the work. A founder may own a customer acquisition goal while relying on a marketing consultant, a sales professional, and a product developer to complete different parts of the project.

What matters is that one person is accountable for keeping the effort moving forward.

For a startup with only one founder, ownership is still important. The founder can assign responsibility to themselves and identify specific time commitments for the work. If several priorities compete for the same hours, the founder can make deliberate decisions about what gets done first.

A useful goal-setting document should include the objective, its measurable results, the person responsible, the deadline, and the next action.

This simple structure reduces confusion and makes it easier to identify problems before they become serious.

6. Review Progress Every Week

Setting goals at the beginning of a quarter and checking them again three months later is rarely enough for an early-stage startup.

Circumstances change quickly. A customer may reveal a major product problem, a promising sales opportunity may require immediate attention, or an unexpected expense may affect the company’s plans.

Weekly progress reviews give founders an opportunity to identify these changes and adjust their work before a small problem becomes a major setback.

A weekly review doesn’t need to be a lengthy meeting. A founder can set aside 30 to 60 minutes to review the company’s most important goals, evaluate progress, and decide what needs attention during the coming week.

For each goal, consider three questions:

  • What progress did we make? Review the actual results and compare them with the milestones established during planning.
  • What is preventing progress? Identify obstacles, resource limitations, delayed decisions, or assumptions that may no longer be valid.
  • What needs to happen next? Establish the specific actions that will move the goal forward during the coming week.

This is where a startup’s operating system becomes particularly useful. A consistent review process connects strategic priorities with everyday work and gives founders a regular opportunity to make informed decisions.

GrowthCraft’s approach to startup planning and operating discipline reinforces the value of connecting goals, milestones, accountability, and regular progress reviews. For first-time founders, this can help turn business planning into an ongoing management practice rather than a document that gets revisited only when something goes wrong.

The OKR resources from What Matters can also help founders understand how regular check-ins support goal execution.

For a more structured approach, connect the weekly review to a CEO scorecard. A scorecard can show a small number of important business indicators, such as cash position, customer acquisition, product milestones, and current priorities. This makes it easier to see where the business is progressing and where the founder needs to intervene.

A weekly review should result in clear decisions and next steps, not simply a discussion of what happened.

7. Know When to Change a Goal

Commitment is important, but continuing to pursue a goal that no longer makes sense can waste valuable startup resources.

Early-stage companies operate with considerable uncertainty. Founders make decisions based on assumptions about customers, markets, product requirements, and available resources. As they gather evidence, some of those assumptions will prove incorrect.

For example, a startup may set a goal of launching a particular product feature within 60 days. During development, customer interviews may reveal that another feature is more important. Continuing to prioritize the original feature simply because it was part of the initial plan may not be the best use of time.

Changing a goal isn’t necessarily a sign of failure. It can be a sign that the founder is responding to new information.

However, founders should distinguish between a goal that needs to change and a goal that is simply difficult. Abandoning an objective every time progress slows can prevent a startup from accomplishing anything meaningful.

Before changing a goal, evaluate the evidence. Has the market changed? Have customer needs become clearer? Are the resources required no longer available? Has the company discovered that its original assumptions were incorrect?

If the goal remains relevant but progress is slow, the solution may be to change the execution plan rather than the objective itself.

If the underlying business assumption is no longer supported by evidence, revising the goal may be appropriate.

Document why a goal changed, what was learned, and what the company will do differently. This creates a useful record of decisions and helps prevent the same mistakes from recurring.

The purpose of goal management is not to follow a plan regardless of circumstances. It’s to help the company make consistent progress while learning and adapting.

Turning Startup Goals Into a Repeatable Operating System

Successful goal setting isn’t a one-time exercise. It should become part of how a startup operates.

Founders can begin by establishing a 90-day planning cycle. At the start of each cycle, identify the company’s most important objectives, define measurable results, assign ownership, and establish milestones. Each week, review progress and determine what needs to happen next.

This approach connects long-term business ambitions with the decisions founders make every day. It also creates a natural connection between goal setting, the startup operating system, and the CEO’s weekly scorecard.

For first-time founders, the benefit is greater clarity. Instead of constantly reacting to the latest problem or opportunity, they have a framework for deciding where to focus their attention.

GrowthCraft supports this kind of practical approach to building a business. Through its startup resources, founder community, workshops, and advisor support, founders can develop the planning and operating habits needed to move from an idea to a functioning company.

The objective isn’t to create a perfect plan. It’s to build a system that helps founders make better decisions, learn from their experiences, and consistently move their businesses forward.

Frequently Asked Questions

1. Why do startup goals often fail?

Startup goals frequently fail because they are too vague, overly ambitious, or disconnected from the resources available to achieve them. Goals also lose momentum when founders establish too many priorities, fail to assign ownership, or neglect to review progress. Clear objectives, measurable results, and consistent accountability help address these problems.

2. How many goals should an early-stage startup have?

An early-stage startup should generally focus on two or three major objectives during a 90-day planning cycle. The exact number depends on the company’s resources and complexity. Limiting priorities helps founders concentrate their time and attention on the outcomes that matter most.

3. How often should startup founders review their goals?

Founders should review their most important goals weekly. A weekly review helps identify obstacles, measure progress, and establish immediate next steps. A more comprehensive review at the end of each month or quarter can help determine whether the goals and underlying assumptions remain relevant.

4. What is the difference between a startup goal and a milestone?

A goal describes an important outcome the startup wants to achieve. A milestone is a significant step toward achieving that outcome. For example, acquiring 20 paying customers could be a goal, while completing 50 customer demonstrations could be a milestone along the way.

5. When should a startup change its goals?

A startup should consider changing a goal when new evidence challenges its original assumptions, business priorities change, or the resources required are no longer available. However, founders should distinguish between a goal that is no longer relevant and one that simply requires more time or a different execution strategy.

GrowthCraft Links

A connected resource library:

1. The Startup CEO’s Weekly Scorecard: The One Meeting Every Startup Founder Should Never Skip Link from the weekly progress review section. This provides readers with a practical way to monitor their goals.

2. Your Startup Doesn’t Need More Tools. It Needs Better Workflows. Link from the sections on priorities and execution. This reinforces the importance of having processes that support the work.

3. The Startup Meeting Guide Nobody Teaches You Link from the section on weekly reviews to help founders structure productive meetings.

4. How to Build a Company Culture Before You Have a Company Link from the ownership section to explore how accountability and responsibility can become part of a startup’s culture.

Primary resources referenced in the blog

1. What Matters

Referenced in article

Objectives and Key Results (OKRs)

Explains how to define objectives and measurable key results, track progress, and maintain focus on outcomes rather than activities.

What Matters website

What Are OKRs? Definition and Examples

Additional recommended resources

These resources provide further support for the article’s discussion of goal setting, prioritization, accountability, and execution.

2. Atlassian

Kanban and limiting work in progress

Explains how visualizing work and limiting the number of tasks in progress can help teams improve workflow and focus.

Kanban: A guide to the methodology

3. Asana

SMART goals

A practical guide to creating specific, measurable, achievable, relevant, and time-bound goals. Useful for founders turning broad ambitions into actionable objectives.

How to write SMART goals

4. Harvard Business Review

Goal setting and management

Provides research-based perspectives on goal setting, employee performance, and organizational management.

Harvard Business Review website

Search its articles for goal setting, performance management, and execution.

5. The Kanban Guide

Managing work and workflow

An additional reference for understanding work in progress, workflow management, and the importance of making work visible.

Kanban Guides

Why Most Startup Goals Fail Before the Work Even Begins Read More »

Early-stage startup founders reviewing a pitch deck, financial projections, and business plans around a conference table.

The Best Pitch Deck Outline: A Step-by-Step Guide for First-Time Startup Founders

Early-stage startup founders reviewing a pitch deck, financial projections, and business plans around a conference table.
A clear pitch deck helps startup founders communicate their business opportunity, demonstrate progress, and explain their funding needs.

The Best Pitch Deck Outline: A Step-by-Step Guide for First-Time Startup Founders

A great pitch deck does more than explain what your startup does. It tells a compelling story about a problem worth solving, a business worth building, and a team capable of making it happen.

For early-stage, first-time startup founders, creating that story can feel overwhelming. What should you include? How much financial detail is enough? How do you demonstrate that your idea has potential when you are still developing the product or finding your first customers?

The good news is that you do not need 30 slides filled with complicated charts and financial projections. A focused, well-structured pitch deck can communicate your opportunity in 10 to 12 slides.

Think of your pitch deck like a movie trailer. It should introduce the opportunity, build interest, demonstrate why your solution matters, and leave investors wanting to learn more. It is not meant to tell your entire business story. It is meant to earn the next conversation.

This guide walks you through the best pitch deck outline, explains what belongs on each slide, and provides actionable advice for turning your startup idea into a clear, credible presentation.

What Is a Startup Pitch Deck?

A startup pitch deck is a concise presentation that explains your business opportunity to potential investors, partners, or other stakeholders. It typically covers the problem, solution, product, market, business model, competition, traction, team, and financial needs.

Although pitch decks are often associated with fundraising, the process of creating one is also valuable for founders who are not yet ready to raise money. It forces you to clarify your assumptions, identify what you still need to learn, and explain why your business deserves attention.

Successful startups such as Airbnb and Uber have used investor presentations to communicate their business opportunities. Their original decks are useful examples of how founders can explain a business model, market opportunity, and customer need in a relatively compact format. However, there is no single universally successful deck template. Your presentation should reflect your company’s stage, business model, and fundraising objectives.

For most early-stage startups, a 10-slide core presentation is a practical starting point. You can expand it to 12 slides when your team, product, or financial information deserves additional attention.

The Core 10-Slide Pitch Deck Outline

The following outline combines the familiar 10-slide structure with the practical details founders need to explain their product, demonstrate traction, and make a clear funding request. It follows the broad logic of Sequoia Capital’s business-planning and pitching guidance, with additional slides and detail to suit an early-stage fundraising conversation.

Slide 1 – Introduction / Cover

1. Introduction: What does your company do?

Your opening slide should make it immediately clear who you are and what your company does. Include your company name, logo, and a concise, one-sentence description of the value you provide.

Avoid vague statements such as “Revolutionizing the future of business.” Instead, explain what you do in language a potential customer or investor can understand. For example, a home-sharing startup might say, “We help travelers find places to stay with local hosts.”

Actionable tip: Complete this sentence: “We help \(specific customer\) solve \(specific problem\) by \(your approach\).” Use it as a starting point for your tagline. Your opening should establish context, not require the investor to guess what the business is.

Slide 2 – The Problem

2. The Problem: What needs to change?

Investors need to understand the customer pain your business is addressing. Identify the specific people or organizations experiencing the problem, explain what makes it difficult, and show why existing ways of dealing with it fall short.

Use evidence whenever possible. Customer interviews, survey results, industry research, operational data, or a short customer story can help establish that the problem is real. For a business-to-business startup, you might explain how a manual process creates delays, increases costs, or limits a company’s ability to serve customers.

Do not simply claim that “everyone has this problem.” Define the target customer and explain how frequently the problem occurs, how serious it is, and what it costs in time, money, or missed opportunities.

Actionable tip: Speak with potential customers and document their actual experiences. Separate what they told you from what you believe is happening. A specific, well-supported problem is more useful than a dramatic but unsubstantiated claim.

Slide 3 -The Solution

3. The Solution: How do you solve the problem?

Introduce your product or service as the direct response to the problem on the previous slide. Explain what changes for the customer when they use your solution and why your approach is meaningfully different from the alternatives.

Keep the explanation focused on the primary benefit. A long list of features can make it difficult to understand the central value proposition. Instead, describe the key action your product enables and the outcome it is designed to deliver.

For example, rather than saying, “Our platform includes automation, reporting, and AI-powered analytics,” explain how the platform helps a particular customer complete a time-consuming task with less manual work.

Actionable tip: Write one sentence that connects the problem directly to your solution. If the relationship is not obvious, revisit the problem statement or simplify the solution explanation.

Slide 4 – Product / Demo

4. Product / Demo: What does it look like in action?

Give investors a tangible understanding of what you are building. A clear screenshot, prototype, short demonstration, or simple workflow diagram can help turn an abstract idea into something they can see and understand.

Focus on the primary use case. Show how a customer begins, what they do with your product, and what result they receive. You do not need to demonstrate every feature. Choose the part of the experience that best illustrates your value proposition.

If your product is still being developed, be transparent. Label conceptual screens as mockups and explain what is already built, what is being tested, and what remains to be completed.

Actionable tip: Prepare a short, reliable demonstration that can be understood without a lengthy technical explanation. Keep a backup screenshot or recorded demo available in case your live presentation encounters technical problems.

Slide 5 – Market Size

5. Market Size: How large could this opportunity become?

Investors need to understand whether your startup is addressing a sufficiently meaningful market and which portion you can realistically serve. The common framework uses three related measures: TAM, SAM, and SOM.

TAM: Total Addressable Market

The total demand or revenue opportunity if your product or service could serve the entire relevant market.

SAM: Serviceable Available Market

The portion of that market your business model, product, geography, and target customer definition allow you to serve.

SOM: Serviceable Obtainable Market

The portion of the SAM you believe you can realistically capture over a defined period, considering competition, resources, and execution.

A large market number by itself does not establish a viable business. Explain how you calculated your estimates and what assumptions support them. A bottom-up calculation, such as the number of potential customers multiplied by a defensible annual revenue per customer, can make the opportunity easier to evaluate.

Actionable tip: Identify your initial ideal customer profile, estimate how many such customers exist in your reachable market, and explain how you arrived at the numbers. Cite the underlying data and clearly label estimates as estimates.

Slide 6 – Business Model

6. Business Model: How will your startup make money?

Explain who pays you, what they pay for, and how often revenue is generated. Your model might involve monthly subscriptions, annual contracts, transaction fees, licensing, usage-based pricing, or one-time purchases.

Keep the explanation simple enough that someone unfamiliar with your industry can follow it. If you charge a monthly subscription, show the price or pricing range, who buys it, and what the customer receives. If your business depends on transactions, explain how you earn revenue from each transaction.

Where you have reliable information, introduce basic unit economics. These may include customer acquisition cost, average revenue per customer, gross margin, retention, and customer lifetime value. At the earliest stages, these figures may be assumptions rather than established metrics. Label them accordingly.

Actionable tip: Build a simple model showing how one customer generates revenue and what it costs to serve that customer. Explain what you still need to validate before assuming the model can scale.

Slide 7 – Why Now?

7. Why Now? What makes this the right time?

Explain what has changed to make your solution possible, necessary, or commercially relevant now. This could be a new technology, a change in customer behavior, a regulatory development, lower operating costs, or a shift in the way businesses work.

The goal is to connect a real market change to your specific opportunity. For example, if a new technology makes a previously expensive process affordable, explain how that changes the economics for your target customer.

Avoid relying on broad statements such as “AI is growing” or “digital transformation is accelerating.” Those statements do not explain why your particular business has an opportunity today.

Actionable tip: Identify one or two specific changes, provide credible evidence for them, and explain how each affects customer demand, product feasibility, or your ability to compete. If your timing argument is weak, investigate whether the customer problem or business model needs further validation.

Slide 8 – Competition

8. Competition: What alternatives do customers have?

Every startup competes with something, even if no other company offers the exact same product. Customers may use an established competitor, a different type of software, an outside service provider, an internal process, or simply continue doing nothing.

Identify the alternatives your target customers actually consider. Compare the factors that matter to them, such as price, ease of use, implementation time, capabilities, or customer support. Then explain where your approach differs and why that difference matters.

A comparison matrix can make this information easier to digest but avoid giving yourself an automatic checkmark in every category. Unsupported claims of superiority can undermine the credibility of the entire presentation.

Actionable tip: Ask potential customers what they use today and why. Include direct competitors and the status quo. Explain your current advantage and distinguish it from advantages you hope to develop in the future.

Slide 9 – Traction

9. Traction: What evidence shows that your startup is progressing?

Traction is evidence that your startup is making progress toward building a viable business. For a company with paying customers, this might include revenue growth, customer retention, repeat purchases, or expansion within existing accounts.

For an idea-stage or pre-revenue startup, traction can take other forms. You might show completed customer interviews, prototype testing, letters of intent, pilot commitments, waitlist activity, or measurable progress in product development. The important thing is to explain what the evidence actually demonstrates.

Distinguish between interest and commitment. Someone joining a waitlist is not the same as someone paying for a product. A positive interview is not the same as a signed customer agreement. Investors need to understand the difference.

Actionable tip: Select a small number of meaningful metrics, show how they have changed over time, and state the period covered. Include definitions and avoid mixing different types of evidence into a single growth figure.

Slide 10 – The Ask & Financials

10. The Ask & Financials: What do you need, and what will it accomplish?

Finish your core presentation by stating what you are asking investors to provide and what you intend to accomplish with that support. If you are raising capital, specify the amount, the type of financing if known, and the milestones the funding is expected to support.

Explain how much runway the raise is designed to provide, based on your planned spending and assumptions. Then identify the three major milestones you expect to achieve. These might include launching a commercial product, reaching a defined number of paying customers, or completing a technical validation.

Include a simple three-year financial forecast showing expected revenue, major expenses, and cash needs. Your projections should connect to your customer acquisition assumptions, pricing, hiring plans, and other operating drivers. Avoid presenting speculative revenue growth as if it were guaranteed.

Actionable tip: Make sure the numbers agree across your deck. The amount you are raising, expected monthly spending, runway, hiring plan, and milestones should tell one consistent story. Be prepared to explain the assumptions behind your forecast and what you would change if results are slower than expected.

Two Optional Slides Worth Considering

The 10-slide outline is a starting point, not a rule. Depending on your company’s stage and the story you need to tell, two additional slides can make the presentation more complete.

Optional Slide 11: The Team

Investors are evaluating not just the opportunity, but also the people working to make it happen. Introduce the founders and key team members, emphasizing relevant experience, technical knowledge, industry relationships, or previous accomplishments that connect directly to the business.

For a first-time founder, a lack of previous startup experience does not mean you have nothing to show. Relevant customer knowledge, a working prototype, industry expertise, and the ability to learn quickly can all help explain why you are positioned to pursue the opportunity.

If you have advisors, explain their actual contributions. An advisor who has helped validate your market or establish important industry relationships is more meaningful than a list of impressive names without context.

Optional Slide 12: Vision and Milestones

Close with a clear picture of what the company could become if the strategy works. Explain the larger opportunity beyond your initial product or customer segment, while connecting that future to the practical milestones you need to achieve first.

For example, a startup might begin by solving one workflow problem for a specific type of customer, then expand into adjacent workflows or customer segments after validating demand.

Your vision should communicate ambition without replacing the evidence and execution plan presented in the rest of the deck.

How to Make Your Pitch Deck More Effective – A well-structured deck is only the beginning. How you communicate the information can determine whether investors understand your opportunity.

Tell one connected story – Each slide should build on the previous one. The problem establishes why something needs to change. The solution explains what you propose to do. The product demonstrates how it works. The market and business model explain the opportunity, while traction and financials help establish what you have accomplished and what you need next.

If your slides feel like unrelated sections of a business plan, revisit the narrative. Your goal is to make the connection between customer need, business opportunity, and execution clear.

Use evidence instead of unsupported claims – Whenever possible, support important statements with customer feedback, research, product results, financial data, or other credible evidence. Identify the source and time period for key statistics.

Be especially careful with market size, customer demand, competitive advantages, and financial forecasts. Clearly distinguish what you know, what you estimate, and what you still need to validate.

Make every slide easy to understand – Use a clear headline, one primary message, and visuals that support that message. Avoid filling slides with paragraphs of tiny text or complicated charts that require lengthy explanations.

A useful editing exercise is to read only the slide headlines. They should communicate the basic story of your startup from beginning to end.

Adapt the deck to your company’s stage – An idea-stage startup will not have the same evidence as a company with recurring revenue and established customers. That is expected.

An early-stage founder can focus on customer discovery, the problem’s significance, product validation, market assumptions, and the milestones required to move forward. A startup with customers can provide more detail on revenue, retention, acquisition costs, and repeatable growth.

The important thing is to present the evidence you actually have, rather than trying to make your startup look more mature than it is.

How GrowthCraft Can Help You Build a Better Pitch Deck

Creating a pitch deck is not simply a presentation-design exercise. It requires decisions about your customer, market, product, business model, financial assumptions, and growth strategy.

For a first-time founder, those decisions can be difficult to evaluate independently. You may understand your technology extremely well but need help explaining its commercial value. Or you may have a compelling customer problem but still need to validate the market size, pricing, and path to revenue.

This is where GrowthCraft can serve as a resource.

GrowthCraft supports early-stage founders as they work through the interconnected parts of building a business, including business growth, market fit, financial structure, and legal protection. Its approach to founder education, advisor support, and peer learning can help founders develop the thinking behind their pitch, not just the slides themselves.

Through access to advisors with different areas of expertise, founders can get perspectives on questions such as:

  • Market and customer validation: Are you solving a meaningful problem for a clearly defined customer, and what evidence supports that conclusion?
  • Business model: Does your pricing and revenue model make sense for the customer and the way you plan to operate?
  • Financial planning: Are your spending assumptions, runway, and milestones consistent with your fundraising request?
  • Sales and marketing: Can you explain how you intend to reach customers and turn interest into revenue?
  • Legal and business structure: Have you considered the foundational business and intellectual property questions relevant to your startup?

The benefit of working with multiple advisors is the opportunity to examine your business from different perspectives. A market opportunity that looks attractive in a presentation still needs to make sense operationally, financially, and commercially.

GrowthCraft’s founder community and peer-learning opportunities can also give you a place to practice explaining your business, receive feedback, and refine your story before sharing it with potential investors.

The goal is to build a pitch deck that reflects a business you understand, a set of assumptions you can defend, and a plan you are prepared to execute.

Frequently Asked Questions About Startup Pitch Decks

1. How many slides should a startup pitch deck have?

A 10-slide core deck is a practical starting point for many early-stage startups. Some founders expand it to 12 slides to include a dedicated team slide and a more detailed vision or milestone slide. The appropriate length depends on your business and the purpose of the presentation.

2. What should a pitch deck include if my startup has no revenue?

An idea-stage or pre-revenue startup can focus on the customer problem, proposed solution, product prototype, market opportunity, business model, competitive alternatives, and founding team. Include evidence from customer interviews, prototype testing, pilot discussions, or other validation efforts where available. Be clear about what is proven and what remains an assumption.

3. Should I include financial projections in my pitch deck?

Yes, when you are seeking investment, a financial overview can help explain how the business may develop and what resources it needs. A simple three-year forecast is a useful starting point for many early-stage founders. Explain the assumptions behind revenue, expenses, hiring, and cash requirements rather than presenting projections as guaranteed outcomes.

4. What is the difference between TAM, SAM, and SOM?

TAM is the total addressable market for your product or service. SAM is the portion your business can serve based on its offering and operating model. SOM is the portion of that serviceable market you realistically expect to capture within a defined period. These measures help explain the size of the opportunity and the scale of your initial business goals.

5. What is the most important part of a startup pitch deck?

There is no single slide that matters equally for every startup. The deck needs to communicate a connected business case: a meaningful customer problem, a compelling solution, a credible market opportunity, and a team with a realistic plan for execution. The most important emphasis depends on what your startup has already demonstrated and what investors need to understand.

Final Checklist: Is Your Pitch Deck Ready?

Pitch deck readiness

0 of 11

  • I can explain what my company does in one clear sentence.
  • The customer problem is specific and supported by evidence.
  • My solution directly addresses that problem.
  • The product or prototype is easy to understand.
  • My market sizing assumptions are transparent and defensible.
  • I can explain who pays and how the business makes money.
  • I have a specific, evidence-based reason for why now.
  • I understand direct competitors and existing alternatives.
  • My traction metrics accurately reflect our stage.
  • My funding request, runway, milestones, and forecast are consistent.
  • I have practiced presenting the story and answering questions.

Conclusion

The best pitch deck outline is one that helps an investor understand your startup’s opportunity without making them work to connect the dots.

Start with a clear explanation of what you do. Show the problem, introduce your solution, demonstrate the product, and explain the market and business model. Then establish what makes the timing relevant, how you compare with alternatives, what progress you have made, and what you need to accomplish next.

For first-time founders, the real value of building a pitch deck is the thinking that happens along the way. Every slide gives you an opportunity to test an assumption, identify a gap, or make your business strategy clearer.

Use the outline as a working guide. Refine it as you learn more about your customers, product, and market. Resources such as GrowthCraft can help you work through those business questions with advisors and fellow founders, so your pitch becomes more than a presentation. It becomes a clearer plan for building your company.

Sources and Further Reading

These resources provide additional context for the pitch deck structure and examples discussed in this guide.

Writing a Business Plan : Sequoia Capital

A foundational guide covering company purpose, customer problem, solution, timing, market potential, competition, business model, team, financials, and vision.

Recommended Pitch Deck Ordering : University of Victoria, Gustavson School of Business

A comparison of observed pitch deck ordering and Sequoia’s recommended sequence.

A Practical Investor Deck Built From Sequoia’s Pitching Framework : Lunera

An independent adaptation discussing how founders can translate pitching principles into a practical investor presentation.

Sequoia Capital Pitch Deck Template (PDF) : Historical template reproduction

A circulated version of the familiar 10-section outline. Use it as a reference, rather than assuming it is a current official slide-design template.

The Best Pitch Deck Outline: A Step-by-Step Guide for First-Time Startup Founders Read More »

Early-stage startup founder working with a small team around a table while building company culture and shared values

How to Build a Company Culture Before You Have a Company

Early-stage startup founder working with a small team around a table while building company culture and shared values
Company culture starts with the behaviors, decisions, and expectations founders establish before a startup begins to grow.

How to Build a Company Culture Before You Have a Company

Most founders think about company culture after they start hiring. That is already too late.

Culture does not begin when you hire your tenth employee. It does not begin when you move into an office, create an employee handbook, or put a list of values on your website.

Culture starts with the decisions you make when nobody is watching.

For an early-stage startup founder, that means company culture is already being created before there is much of a company at all. The way you treat customers, handle mistakes, make decisions, communicate with a co-founder, prioritize your time, respond to bad news, and decide who gets hired all become signals about what the company considers normal.

This matters because early employees do not just join a startup. They help define it. Their behaviors become examples for the people who come after them. Eventually, those behaviors become habits, and those habits become the culture.

Research and startup experience consistently point to the same idea. Culture is not primarily what a company says about itself. It is reflected in who gets hired, who gets recognized, how leaders behave, and what the organization repeatedly rewards. Y Combinator has described culture as something that begins with founders and evolves as the company grows.

For a first-time founder, the good news is that you do not need a large team, an HR department, or an expensive culture program to start building a healthy company culture.

You need intention.

Culture Starts With the Founder

The earliest version of your company’s culture is probably going to look a lot like you.

That is not necessarily a bad thing. In fact, it is almost unavoidable. If you respond to problems calmly, your early team will notice. If you blame people when something goes wrong, they will notice that too. If you admit when you are wrong, ask for help, and listen to uncomfortable feedback, those behaviors become part of the environment.

The important question is not simply, “What kind of culture do I want?”

A better question is, “What behaviors am I demonstrating every day that other people might copy?”

Imagine a founder who says that transparency is important but avoids discussing difficult financial realities with the team. The company may have “transparency” listed as a value, but employees will quickly learn that difficult information is kept behind closed doors.

Now imagine a founder who tells the team when something has gone wrong, explains what is known and unknown, and invites people to help solve the problem. That founder is teaching transparency without needing to give a speech about it.

This is one reason culture should be considered an operating system for a startup rather than a collection of slogans.

Before you hire your first employee, take some time to write down how you want the company to operate. Think about how you want people to treat customers, challenge ideas, handle mistakes, communicate problems, and make decisions.

Then ask yourself whether your own behavior consistently demonstrates those expectations.

If it does not, fix the behavior before you try to fix the culture.

The Behaviors You Reward Become the Culture

Founders often assume culture is created by what they say is important. In practice, what you reward may be much more powerful.

Suppose you say that collaboration matters, but the person who works around everyone else and gets things done alone is consistently praised. Your team will learn that individual achievement matters more than collaboration.

Suppose you say that customer feedback is important, but you celebrate the team for shipping features while ignoring whether customers actually use them. Your team will learn that shipping matters more than learning.

Every startup has limited resources. You cannot reward everything. That makes your choices especially important.

Recognition does not always mean money or formal awards. It can be as simple as telling someone, “That was exactly the kind of ownership I want to see here.” It can mean giving someone more responsibility because they handled a difficult situation well. It can also mean addressing behavior that does not fit the company, even when the person producing that behavior is technically strong.

Y Combinator founder and CEO discussions make this point clearly: culture is influenced by who you hire, who you recognize, who you promote, and who you ultimately decide should not remain on the team.

This gives founders a practical test.

When something goes well, ask yourself what behavior made it possible. When someone succeeds, ask what they did that you want repeated. Then make sure you recognize those behaviors consistently.

Over time, people will understand what the company actually values.

How Decisions Get Made

One of the most overlooked parts of startup culture is decision-making.

Early-stage companies make decisions constantly. Which customer should you pursue? What should you build next? Should you spend money on a new tool? Should you change the product? Should you hire someone? Should you respond to a difficult customer request?

The way those decisions are made teaches employees what the company expects from them.

If every decision has to go through the founder, you are creating a culture of dependency. If employees are expected to make decisions but are punished whenever something goes wrong, you are creating a culture of caution.

Instead, establish some basic decision principles early.

For example, you might expect people to make decisions as close to the customer as possible. You might want employees to use available evidence rather than waiting for perfect information. You might expect someone making a decision to explain the reasoning behind it and take responsibility for the outcome.

This does not mean every decision needs a formal process. Startups need speed. But people should understand how you want decisions to happen.

A healthy startup culture does not eliminate disagreement. It creates a productive way to disagree.

You want people who can say, “I think this is the wrong direction,” explain why, listen to opposing viewpoints, and then support the final decision once it has been made.

That kind of environment can become a competitive advantage because people are contributing their judgment rather than simply waiting for instructions.

Communication Expectations Start Early

Communication problems rarely appear suddenly when a startup reaches 50 employees. They usually begin much earlier.

When the company is only two or three people, communication can feel effortless because everyone is involved in everything. As more people join, assumptions that once seemed obvious begin to break down.

That is why founders should establish communication expectations before communication becomes a problem.

What does urgent mean? When should someone send a message versus schedule a conversation? Are people expected to respond immediately? How should bad news be communicated? Is it acceptable to disagree publicly? How are decisions documented?

You do not need a 40-page communications policy.

You need shared expectations.

For example, a founder might establish that bad news should be communicated quickly, disagreements should be addressed directly, important decisions should be documented, and people should not be expected to be constantly available simply because they work at a startup.

These expectations become especially valuable as the company grows because new employees can learn how the organization communicates instead of trying to figure it out through trial and error.

Y Combinator’s guidance on early-stage HR also emphasizes the importance of creating ways for employees to raise concerns and provide feedback before problems become larger cultural issues.

Create Values That Are Actually Useful

“Integrity.”

“Innovation.”

“Excellence.”

“Teamwork.”

There is nothing wrong with these words. The problem is that almost every company could use them.

Useful company values should help people make decisions.

Instead of simply saying “customer focused,” explain what that means in practice. Does it mean talking to customers every week? Does it mean solving the customer’s problem rather than selling the easiest product? Does it mean customer feedback can change the product roadmap?

Instead of “ownership,” explain the behavior. Perhaps ownership means bringing problems forward with potential solutions, following through on commitments, and taking responsibility when something does not work.

A good value should help answer a question when the founder is not in the room.

Y Combinator has highlighted the importance of defining values early and using them as a practical reference point for alignment and hiring.

Try creating three to five values and, beneath each one, write two or three sentences describing what the value looks like in everyday behavior.

Then use those values.

Use them when hiring. Use them when recognizing employees. Use them during performance conversations. Use them when resolving disagreements.

If a value never affects a decision, it probably is not functioning as a value.

Hire for Culture Contribution, Not Culture Cloning

“Culture fit” can be a dangerous phrase if it means hiring people who think, communicate, and behave exactly like the founder.

You do not want clones.

A strong startup needs people who share important principles while bringing different experiences, perspectives, skills, and approaches to problems.

This distinction matters. Hiring for cultural alignment should mean asking whether someone can operate effectively within the company’s principles, not whether you would enjoy having a beer with them.

Y Combinator’s discussions on startup hiring make a similar distinction between skills and values, emphasizing the need for an intentional hiring process rather than relying entirely on gut instinct.

Before making an early hire, identify both the capabilities you need and the behaviors you want the person to demonstrate.

Then ask questions that reveal how the candidate actually operates.

Instead of asking, “Are you a team player?” ask about a time they disagreed with a teammate and what happened next.

Instead of asking, “Are you comfortable with ambiguity?” ask about a situation where they had incomplete information and had to make a decision.

Instead of asking, “Do you take ownership?” ask about a significant mistake they made and how they handled it.

You are looking for evidence, not the right interview answer.

Most importantly, remember that your first few hires have an outsized influence on the culture that develops later. Hiring the wrong person because you desperately need help can create problems that are much harder to fix later.

Protect Culture During Growth

The culture that works with five people may not work exactly the same way with 25 people.

That does not mean your culture has failed. It means the company has changed.

As startups grow, informal communication becomes less reliable. Founders cannot personally reinforce every behavior. New managers begin shaping teams. Employees start making decisions without direct founder involvement.

The answer is not to freeze the culture in place.

The answer is to protect the principles while allowing the practices to evolve.

Y Combinator has noted that startup culture naturally changes as companies grow and that founders need mechanisms that help culture evolve rather than assuming the culture will remain exactly as it was in the beginning.

That might mean moving from informal conversations to regular one-on-ones. It might mean documenting decision-making principles. It might mean creating a more structured hiring process. It might mean conducting regular employee feedback sessions.

The goal is consistency, not rigidity.

You should also watch for the difference between the culture you intended to build and the culture employees are actually experiencing.

Ask your team questions such as:

“What’s something we do here that you hope never changes?”

“What is something we say is important but do not consistently demonstrate?”

“What behavior gets rewarded around here?”

“What makes it difficult to do your best work?”

“What would you change about how we operate?”

The answers can reveal problems that leadership cannot see from the inside.

Culture Is an Early-Stage Operating Decision

Company culture can sound like a topic reserved for large organizations with HR departments and hundreds of employees.

It is not.

For an early-stage founder, culture is already being created through everyday decisions.

It is in how you treat the first customer who complains. It is in whether you admit a mistake. It is in how you talk about competitors. It is in whether people can challenge your ideas. It is in who gets hired when you are desperate for help. It is in what you celebrate when things go well.

That is why building culture before you have a company is not about creating a polished values document.

It is about deciding what kind of company you want to build and then behaving accordingly.

This is also where a resource such as GrowthCraft can be useful for first-time founders. GrowthCraft’s broader approach is built around helping early-stage founders think through the business beyond simply building a product. Business growth, market fit, financial structure, legal protection, and the decisions that connect those areas all require founders to develop repeatable ways of operating. Culture is part of that foundation.

The earlier you think about those operating principles, the easier it becomes to build a company where people understand not only what they are doing, but how and why they are expected to do it.

You do not need 20 employees to have a culture.

You already have one.

The real question is whether you are building it intentionally.

Frequently Asked Questions

When should a startup founder start thinking about company culture?

Immediately. Culture begins with the founder’s behavior and the decisions made before the first employee is hired. Waiting until the company has a larger team means many behaviors and expectations may already be established.

How many company values should a startup have?

Three to five meaningful values are usually more useful than a long list. The important part is not the number. Each value should describe specific behaviors and help people make decisions when leadership is not present.

What does culture fit mean for a startup?

Culture fit should mean alignment with the company’s fundamental principles and ways of working, not hiring people who are similar to the founder. A strong startup culture should allow for different backgrounds, perspectives, experiences, and working styles while maintaining shared expectations around important behaviors.

Can company culture change as a startup grows?

Yes. In fact, it should evolve. The underlying principles can remain consistent while the systems used to reinforce them change. A five-person startup may rely on informal communication, while a 50-person company may need structured feedback, management practices, and documented decision-making principles.

How can a founder tell whether the culture they want is actually developing?

Look at behavior rather than slogans. Pay attention to who gets recognized, how people handle mistakes, how disagreements are resolved, what information gets shared, how decisions are made, and which behaviors new employees quickly adopt. Direct employee feedback can also reveal gaps between the intended culture and the actual employee experience.

Sources and Further Reading

The following resources informed this article and provide additional guidance for founders building teams and company culture:

How to Build a Company Culture Before You Have a Company Read More »

Early-stage startup founder reviewing limited business data and making a strategic decision with notes, charts, and customer insights.

How to Make Better Decisions When You Don’t Have Enough Data

Early-stage startup founder reviewing limited business data and making a strategic decision with notes, charts, and customer insights.
Better startup decisions do not require perfect information. They require clear assumptions, useful experiments, and a willingness to learn.

How to Make Better Decisions When You Don’t Have Enough Data

One of the hardest parts of being a startup founder is making decisions before you have enough information to feel confident about them.

Should you build the feature? Change the pricing? Hire someone? Focus on a different customer? Spend money on marketing? Keep pursuing the current idea or change direction?

Established companies can often answer these questions with years of customer data, historical performance, market research, and large teams of specialists. Early-stage startups usually cannot.

That creates an uncomfortable reality for first-time founders: you have to make important decisions with incomplete information.

The goal, however, is not to somehow eliminate uncertainty. You cannot. The goal is to develop a process for making reasonable decisions, testing what you believe, learning quickly, and changing course when the evidence tells you to.

That is one of the most important disciplines a founder can develop.

The Founder Decision Traps

When founders do not have enough data, they tend to fall into a few predictable traps.

The first is making a decision based entirely on instinct. Founder intuition has value. You probably understand the problem you are trying to solve better than most people. But intuition is still a hypothesis. It should not automatically be treated as evidence.

The second trap is looking for information that confirms what you already believe. If you think customers will pay $99 per month, it is easy to focus on the person who says, “That sounds reasonable,” while ignoring the five people who say they would never pay it.

The third is asking for too much information before acting. This is where analysis paralysis begins. The founder keeps researching, interviewing, comparing competitors, building spreadsheets, and collecting opinions because making a decision feels risky.

The fourth trap is confusing activity with learning. You can conduct 50 customer interviews and still learn very little if you are asking vague questions or looking for compliments instead of evidence.

Y Combinator makes a similar point in its guidance for founders: early-stage companies need to maintain a direct connection with users and continually use what they learn to improve the product.

The problem is not that you have too little information.

The problem is that you may not have a process for turning limited information into better decisions.

You May Not Need More Data. You May Need Better Questions.

When founders feel uncertain, their first instinct is often to collect more information.

Instead, start by asking a better question:

What would I need to know to make this decision?

Suppose you are deciding whether to build an advanced reporting feature.

You could spend weeks researching competitors, surveying customers, studying market reports, and analyzing potential revenue.

Or you could identify the core assumption:

“We believe our target customers will use this reporting feature frequently enough that it will increase retention or willingness to pay.”

Now you have something you can test.

Talk to existing users. Ask how they currently solve the reporting problem. Look at how frequently they use related functionality. Create a mockup. Put the proposed feature in front of customers. Ask for a commitment, not just an opinion.

The decision becomes much easier because you have converted a vague question into a specific hypothesis.

Strategyzer’s approach to business testing is built around this idea. Before running an experiment, founders should identify the assumptions that need to be true for the business idea to work, then determine which assumptions are most important and least supported by evidence.

Use Assumptions Instead of Pretending You Know

An assumption is not necessarily a bad thing.

Every startup is built on assumptions.

You assume a particular customer has a problem. You assume the problem is important enough to solve. You assume your solution addresses it. You assume customers will pay. You assume you can acquire customers at a reasonable cost. You assume the product can be built and delivered.

The mistake is not having assumptions.

The mistake is forgetting that they are assumptions.

A useful founder habit is to write important beliefs as statements beginning with:

“We believe that…”

For example:

“We believe that small professional services firms will pay $500 per month for automated reporting.”

“We believe that founders will spend 30 minutes per week reviewing a startup performance dashboard.”

“We believe that customers who use this feature twice per week will be more likely to remain customers.”

This simple exercise changes the conversation. You are no longer arguing about whether an idea is good. You are identifying something that can potentially be proven or disproven.

Strategyzer recommends making hypotheses testable, precise, and discrete so that experiments produce useful evidence.

Prioritize the Assumptions That Could Hurt You Most

Not every unknown deserves your attention.

Some assumptions are minor. Others could kill the business.

Imagine you are building a software product for accountants.

You may have 20 unanswered questions about the business. What should the dashboard look like? Which integrations should you build? What colors should the interface use? Should you offer three pricing tiers?

Those questions may matter eventually.

But one question matters more:

Will accountants actually pay for this solution?

If the answer is no, the other decisions are largely irrelevant.

A useful framework is to evaluate each major assumption according to two dimensions:

How important is this assumption to the business?

How much evidence do we currently have?

The assumptions that are both highly important and poorly supported should receive the most attention.

This is essentially the logic behind assumption mapping, which Strategyzer uses to help teams identify high-risk, low-evidence hypotheses before committing significant resources.

For an early-stage founder, this can become a simple weekly exercise. Ask yourself:

“What do we currently believe that, if proven wrong, would materially change what we are doing?”

That is probably where your next experiment belongs.

Avoid Analysis Paralysis

Analysis paralysis often disguises itself as responsible leadership.

You tell yourself that you are “doing research.”

You are “waiting for more information.”

You are “making sure we get it right.”

But startups operate under uncertainty. Waiting for perfect information can be more dangerous than making a reasonable decision with incomplete information.

The better question is:

Can I make this decision reversible?

If the answer is yes, move faster.

Testing a landing page is reversible. Interviewing 10 customers is reversible. Trying a different pricing page is reversible. Running a small advertising experiment is reversible.

Signing a five-year contract, hiring 30 employees, spending hundreds of thousands of dollars, or building a product architecture that is difficult to change is much less reversible.

This distinction can dramatically improve decision-making.

When the cost of being wrong is low, make the decision quickly and learn.

When the cost of being wrong is high, slow down and gather stronger evidence.

Build Fast Experiments Instead of Large Research Projects

One of the best ways to make decisions with limited data is to create your own data.

You do not necessarily need a large research project.

You need a small experiment designed to answer one important question.

For example, if you believe customers will pay $200 per month for a service, you could spend three months building it.

Or you could test the assumption first.

Talk to 10 potential customers. Present the offer. Ask them about their current spending and alternatives. Then ask whether they would be willing to move forward under a defined set of conditions.

You may discover that the price is wrong.

You may discover that the problem is not painful enough.

You may discover that the customer segment is wrong.

Or you may discover that you were right.

All four outcomes are useful.

The important thing is that you learned something before committing significant resources.

Strategyzer recommends using small experiments to test critical hypotheses and emphasizes that the experiment should be connected directly to the assumption being tested.

Think in Learning Loops

A strong startup does not operate like this:

Decide → Build → Hope

It operates more like this:

Assume → Test → Measure → Learn → Decide → Repeat

This is a learning loop.

The decision you make today does not have to be perfect. It needs to create the opportunity to learn something that improves your next decision.

For example:

You believe a particular customer segment is your best market.

You interview customers and discover that the problem exists, but it is not urgent.

You adjust the positioning.

You run another test.

Customers respond more positively, but pricing remains an issue.

You test pricing.

Now you have a better understanding of the market than you had three weeks earlier.

The startup is becoming smarter through repeated cycles.

Y Combinator has similarly described startup execution as a process of forming hypotheses, testing them, drawing conclusions, and repeating the cycle.

This is why early-stage startups should value speed of learning, not simply speed of execution.

Know What Counts as Evidence

Not all information deserves equal weight.

A customer saying, “I love this idea,” is interesting.

A customer giving you a credit card is stronger evidence.

A customer using the product repeatedly is stronger evidence still.

A customer paying, continuing to use it, and referring someone else is powerful evidence.

This does not mean qualitative feedback is unimportant. Early-stage founders often have too little quantitative data to rely exclusively on metrics. Conversations can reveal motivations, objections, frustrations, and problems that analytics cannot explain.

But you should understand the difference between what someone says they will do and what they actually do.

When possible, design your experiments around behavior.

Instead of asking, “Would you use this?”

Ask, “How do you solve this problem today?”

Instead of asking, “Would you pay $100 for this?”

Ask, “What are you currently spending to solve this problem?”

Instead of asking, “Do you like the feature?”

Ask, “How often would this change what you currently do?”

Y Combinator’s guidance on customer conversations similarly emphasizes asking about real experiences and past behavior rather than relying heavily on hypothetical questions.

Create a Decision Framework

When you are facing a difficult decision, write down five things:

1. The decision.
What exactly are you deciding?

2. The assumption.
What must be true for your preferred decision to work?

3. The evidence.
What do you actually know today, and what are you simply assuming?

4. The test.
What is the fastest reasonable experiment that could increase your confidence?

5. The threshold.
What result would cause you to continue, modify the idea, or stop?

That final question is particularly important.

If you do not define what would change your mind before running the experiment, it is easy to reinterpret the results afterward.

For example:

“We will continue pursuing this customer segment if at least five of the next 10 qualified prospects agree to a paid pilot.”

Now the result has meaning.

If you get eight, you have encouraging evidence.

If you get two, you have a reason to reconsider.

If you get five, you have a more complicated decision that requires additional testing.

The important thing is that you decided in advance what the evidence would mean.

Know When to Change Direction

Changing direction is not necessarily failure.

Sometimes the evidence tells you that your original assumption was wrong.

That is valuable.

A founder should become concerned when the same assumption repeatedly fails and the team keeps finding explanations for why the evidence “doesn’t count.”

That is confirmation bias disguised as persistence.

Changing direction becomes more reasonable when you see patterns such as customers consistently describing a different problem than the one you are solving, repeated difficulty getting customers to pay, engagement that disappears after initial use, or a customer segment that responds much more strongly than your original target.

A pivot does not always mean abandoning the entire company.

Sometimes it means changing the customer.

Sometimes it means changing the problem.

Sometimes it means changing the pricing model.

Sometimes it means changing the delivery method.

Sometimes it means removing features instead of adding them.

The goal is not to remain committed to your first idea.

The goal is to remain committed to solving a meaningful problem and building a viable business.

How GrowthCraft Helps Founders Make Better Decisions

This is an area where GrowthCraft can serve as a valuable resource for first-time founders.

Early-stage founders do not always need another generic business course. Often, they need experienced people who can challenge their assumptions, ask better questions, and provide perspective when they are too close to the problem.

GrowthCraft’s community and mentorship model is designed around helping early-stage founders work through practical business challenges rather than simply giving them information.

That distinction matters.

A founder can read about customer validation, experimentation, financial planning, leadership, or business strategy. The harder part is applying those concepts to the specific situation in front of them.

GrowthCraft provides a place for founders to work through those questions with advisors, peers, workshops, and practical conversations. GrowthCraft

The value is not having someone make the decision for you.

It is having people who can help you think through the decision more clearly.

A Simple Weekly Decision Practice for Founders

Set aside 30 minutes each week to review the decisions currently facing your company.

Choose the one that has the greatest potential impact.

Write down what you believe, what you know, what you do not know, and what would change your mind.

Then ask:

What is the smallest experiment I can run this week that will give me better evidence?

Run it.

Record what happened.

Then make the next decision.

Over time, this creates something more valuable than a collection of answers.

It creates a company that learns.

And for an early-stage startup, that may be one of the most important capabilities you can develop.

You will rarely have enough data.

You can, however, build a better process for making decisions with the data you have, identifying what you do not know, testing your assumptions, and learning faster than the uncertainty around you changes.

That is what good startup decision-making looks like.


Frequently Asked Questions

How do startup founders make decisions without enough data?

Start by identifying the assumption behind the decision. Determine how important that assumption is, how much evidence you have, and what small experiment could provide better evidence. The goal is not certainty. It is making a reasonable decision while creating a path toward better information.

What should founders do when they are stuck in analysis paralysis?

Separate reversible decisions from irreversible ones. If a decision is inexpensive and easy to change, make it quickly and learn from the result. For higher-risk decisions, define the specific information you need before acting rather than collecting data indefinitely.

How can a startup test an idea without spending a lot of money?

Start with the smallest experiment capable of testing the most important assumption. That might involve customer interviews, a landing page, a prototype, a manual service, a paid pilot, or a simple pricing test. The best first experiment is often much smaller than the product you ultimately intend to build.

When should a startup change direction?

Consider changing direction when repeated experiments consistently contradict a critical assumption. Look for patterns rather than one-off negative results. A change in customer segment, problem, pricing, product, or business model may be enough. The goal is to respond to evidence rather than becoming attached to the original plan.

What is the most important decision-making habit for a first-time founder?

Learn to distinguish between what you know, what you believe, and what you need to test. That simple distinction prevents assumptions from becoming accepted as facts and creates a more disciplined approach to uncertainty.


References and Further Reading

How to Make Better Decisions When You Don’t Have Enough Data Read More »

Startup CEO analyzing weekly business scorecard to monitor growth, cash flow, customer performance, and company priorities.

The Startup CEO’s Weekly Scorecard

The Startup CEO’s Weekly Scorecard

The One Meeting Every Startup Founder Should Never Skip
Startup CEO analyzing weekly business scorecard to monitor growth, cash flow, customer performance, and company priorities.

Every startup has moments where everything feels urgent.

One customer wants a feature immediately. A potential investor needs updated financials. A developer discovers a critical bug. Marketing wants more budget. Sales says they need pricing changes.

Before long, the founder spends every day putting out fires.

The problem is not that startups move quickly. Speed is part of building a company. The problem is when the founder loses visibility into the overall health of the business.

Successful CEOs eventually learn an important lesson.

You cannot manage what you never stop to measure.

That is why experienced executives rely on scorecards.

A weekly CEO scorecard is not another spreadsheet. It is a decision-making tool that gives you a complete snapshot of your company every week. Instead of relying on instinct or waiting until monthly board meetings, founders can quickly understand whether the company is moving in the right direction.

If you already have dashboards that track marketing or sales metrics, this scorecard is the next step. Rather than focusing on individual departments, it provides a company-wide executive view that helps founders prioritize what matters most.

For early-stage founders, this habit can become one of the most valuable operating systems they build.

Why Weekly Matters More Than Monthly

Many startups review performance once a month.

Unfortunately, thirty days is a long time when your runway may only be twelve to eighteen months.

Problems grow quickly.

Customer churn accelerates.

Expenses increase.

Sales pipelines shrink.

Hiring issues spread.

By the time monthly reports arrive, many of the decisions have already been made for you.

A weekly review creates a much faster feedback loop.

Instead of asking, “How did we perform last month?” you begin asking, “What needs attention before next week?”

That shift changes how founders lead.

Companies that operate with regular measurement often make better decisions because they discover trends earlier instead of reacting after the damage has already occurred.

This philosophy aligns with recommendations from organizations like the Entrepreneurial Operating System (EOS), where weekly leadership meetings focus on measurable progress, accountability, and solving issues before they become major obstacles.

What Should Every Startup CEO Review Weekly?

While every business has unique goals, most early-stage startups can build an effective weekly scorecard around eight categories.

Together, these provide a balanced picture of company performance.

  1. Metrics

Numbers remove emotion from decision making.

Instead of asking whether the company “feels” like it is growing, founders should identify a small group of measurable indicators that reflect actual progress.

Examples include:

  • Monthly Recurring Revenue (MRR)
  • Weekly sales meetings completed
  • Qualified opportunities added
  • Customer acquisition cost
  • Website conversion rate
  • Product usage
  • Active customers
  • Customer retention

The goal is not to track hundreds of numbers.

The best scorecards often include between eight and fifteen metrics that directly influence company success.

Ask yourself one question:

“If this number changes significantly, would I make a different decision?”

If the answer is no, it probably does not belong on the scorecard.

  1. Priorities

Founders often confuse activity with progress.

Busy teams can complete dozens of tasks while accomplishing very little that actually moves the business forward.

Every week should begin with three to five company priorities.

These are the initiatives that deserve leadership attention above everything else.

Examples include:

  • Launching a beta product
  • Closing three enterprise customers
  • Completing investor materials
  • Hiring a senior engineer
  • Reducing onboarding time

At the weekly review, ask:

  • What was completed?
  • What slipped?
  • What is blocking progress?
  • Does anything need to change?

When priorities stay visible every week, teams become much better at execution because everyone understands what success looks like.

  1. Cash

Revenue is exciting.

Cash is survival.

Many startups fail despite having customers because they run out of working capital before reaching profitability.

Every founder should know several financial numbers without opening accounting software.

These include:

  • Current cash balance
  • Monthly burn rate
  • Remaining runway
  • Accounts receivable
  • Major upcoming expenses

According to research published by CB Insights, running out of cash consistently ranks among the leading reasons startups fail.

Weekly visibility allows founders to make adjustments before financial pressure becomes a crisis.

This may include delaying hiring, reducing discretionary spending, increasing collections, or accelerating revenue-generating activities.

Cash should never be a surprise.

  1. Customers

Customers tell founders the truth about the business.

Every week should include a brief review of customer health.

Rather than simply counting new customers, founders should examine the quality of customer relationships.

Useful questions include:

  • How many customers were added?
  • How many were lost?
  • What feedback appeared repeatedly?
  • Are support requests increasing?
  • Are customers successfully adopting the product?

Patterns matter more than individual complaints.

Three similar customer conversations often reveal a product issue long before analytics confirm it.

Customer insights also help shape product development, pricing decisions, and marketing messages.

Companies that continuously listen to customers generally adapt faster than competitors.

GrowthCraft’s Perspective

One of the biggest challenges first-time founders face is knowing what deserves attention each week.

That is where GrowthCraft adds value.

Rather than overwhelming founders with dozens of disconnected templates and frameworks, GrowthCraft encourages entrepreneurs to build repeatable operating habits that simplify decision making.

A weekly CEO scorecard becomes one of those habits.

It connects leadership discussions with measurable outcomes while helping founders build discipline before their organizations become larger and more complex.

Many founders wait until they have twenty employees before introducing operational rhythms.

GrowthCraft encourages startups to establish these practices from the beginning because simple systems scale far better than reactive management.

  1. Team

No startup succeeds because of one founder. Even in the earliest stages, your team determines how quickly ideas become products, customers become advocates, and challenges become opportunities.

A weekly CEO scorecard should include a short review of team health. This is not intended to replace one-on-one meetings or performance reviews. Instead, it helps you identify patterns that may require attention before they become larger issues.

Some questions to consider each week include:

  • Is everyone clear on the company’s top priorities for the week? A lack of clarity often leads to duplicated work, missed deadlines, and frustration.
  • Are there any blockers preventing team members from making progress? These may include missing resources, unclear requirements, or dependencies on other people.
  • Are key positions adequately staffed? As startups grow, capacity can become a hidden bottleneck long before revenue reflects it.
  • Has anyone demonstrated exceptional performance or gone above and beyond? Recognition reinforces positive behaviors and strengthens culture.
  • Are there any morale concerns that leadership should address? Small issues that go unaddressed can gradually erode trust and engagement.

Strong startup cultures are built through consistent leadership, communication, and accountability. Reviewing team health weekly keeps people at the center of your decision-making rather than treating culture as an afterthought.

  1. Risks

Every startup has risks.

The difference between successful companies and struggling ones is rarely the absence of risk. It is the willingness to identify and address those risks early.

Many founders avoid discussing risks because they believe doing so creates negativity. In reality, acknowledging risks allows you to reduce their impact before they become crises.

Your weekly scorecard should include a section dedicated to identifying your biggest concerns.

Examples might include:

  • A customer representing too much of total revenue.
  • Cash runway falling below a target threshold.
  • Delays in product development.
  • Competitive announcements.
  • Regulatory or compliance changes.
  • Hiring challenges.
  • Supplier or technology dependencies.

A useful exercise is to ask your leadership team one simple question:

“What is most likely to prevent us from achieving our goals over the next 90 days?”

The answers often reveal issues that deserve immediate attention.

By documenting risks each week, founders also create a historical record that helps identify recurring challenges and improve future planning.

  1. Wins

Founders naturally focus on problems.

That mindset is useful for solving challenges, but it can also create the impression that nothing is ever going well.

Celebrating wins helps maintain perspective.

Wins do not have to be massive milestones.

They can include:

  • Signing a new customer.
  • Completing a product release.
  • Receiving positive customer feedback.
  • Hiring a great employee.
  • Achieving a revenue goal.
  • Receiving media coverage.
  • Improving an operational process.

Recognizing progress reinforces momentum.

It also reminds the team that their work is making a difference.

Many startups move so quickly that they immediately shift from one objective to the next without acknowledging what has already been accomplished. Taking just a few minutes to celebrate weekly wins strengthens morale and builds a healthier company culture.

  1. Learning

The best CEOs are continuous learners.

Every week provides new information about customers, competitors, products, leadership, and markets.

Unfortunately, many founders experience those lessons without documenting them.

Your scorecard should include one final question:

What did we learn this week?

The answer might involve:

  • Customer buying behavior.
  • Pricing feedback.
  • Product usability.
  • Sales messaging.
  • Hiring practices.
  • Marketing performance.
  • Internal communication.
  • Leadership decisions.

Over time, these weekly lessons become one of your company’s most valuable knowledge assets.

Instead of repeating mistakes, your organization develops institutional knowledge that supports better decisions as the business grows.

Putting the Weekly Scorecard into Practice

Building a scorecard is relatively simple.

Using it consistently is what creates value.

Consider scheduling a recurring leadership meeting at the same time every week. Many startups choose Monday morning or Friday afternoon because it creates a predictable operating rhythm.

The meeting does not need to be long.

In many cases, 30 to 45 minutes is enough.

A simple agenda might include:

  1. Review last week’s priorities.
  2. Examine key metrics.
  3. Discuss cash position.
  4. Review customer insights.
  5. Evaluate team health.
  6. Identify major risks.
  7. Celebrate wins.
  8. Capture lessons learned.
  9. Confirm next week’s priorities.

The scorecard should fit on one or two pages.

If it takes an hour just to read the document, it has become too complicated.

Remember that the purpose is not reporting.

The purpose is making better decisions.

A Sample Startup CEO Weekly Scorecard

Below is an example of what a simple executive scorecard might include.

Category

Example Measures

Metrics

MRR, qualified opportunities, website conversions, active users

Priorities

Top 3 to 5 strategic initiatives with current status

Cash

Cash balance, burn rate, runway, accounts receivable

Customers

New customers, churn, NPS, support trends, product feedback

Team

Staffing updates, blockers, recognition, morale

Risks

Top three operational or strategic risks

Wins

Customer successes, product milestones, revenue achievements

Learning

Key lessons from customers, team, sales, or product

As your company grows, the scorecard will naturally evolve.

The important part is establishing the discipline now.

Common Mistakes Founders Make

Many founders understand the importance of measurement but unintentionally build scorecards that are difficult to use.

Some of the most common mistakes include:

Tracking too many metrics. More data rarely leads to better decisions. Focus on the handful of numbers that truly influence your business.

Reviewing information without taking action. Every metric should lead to a discussion or decision. If it never influences action, consider removing it.

Ignoring leading indicators. Revenue tells you what already happened. Pipeline growth, customer engagement, and product adoption often tell you what will happen next.

Making the scorecard too complicated. Simplicity increases adoption. A scorecard that leadership actually uses every week is far more valuable than an elaborate dashboard that no one reviews.

Treating the scorecard as a reporting exercise. The goal is not to impress investors or board members. It is to help the leadership team make better decisions faster.

Final Thoughts

The most successful startup CEOs are not necessarily the smartest people in the room.

They are often the most disciplined.

They create habits that provide visibility into the business before problems become emergencies.

A weekly scorecard is one of those habits.

It gives founders a structured way to review performance, monitor cash, understand customers, support their teams, identify risks, celebrate progress, and capture valuable lessons.

Over time, this weekly discipline compounds into better execution, stronger leadership, and more predictable growth.

At GrowthCraft, we encourage founders to build these operational habits early. The companies that scale successfully are rarely relying on instinct alone. They develop repeatable systems that make good decisions easier, align their teams around shared priorities, and create accountability across the organization.

If you are building your startup today, don’t wait until you have a board of directors or a leadership team of twenty people. Start using a CEO weekly scorecard now. Your future company will thank you for it.

Frequently Asked Questions

  1. What is a startup CEO weekly scorecard?

A startup CEO weekly scorecard is a concise executive dashboard that summarizes the health of the business each week. It typically includes company metrics, strategic priorities, cash position, customer insights, team updates, business risks, recent wins, and lessons learned to support faster and more informed decision making.

  1. How many metrics should a startup track?

Most early-stage startups benefit from tracking between 8 and 15 meaningful metrics. These should be directly tied to business performance and influence leadership decisions. Avoid tracking data simply because it is available.

  1. How often should founders review their scorecard?

Weekly reviews provide the best balance between staying informed and avoiding unnecessary administrative work. A consistent weekly cadence allows founders to identify trends and address problems before they become significant.

  1. What is the difference between a KPI dashboard and a CEO scorecard?

A KPI dashboard often focuses on operational or departmental performance, such as marketing or sales metrics. A CEO scorecard provides a broader executive view by combining financial health, strategic priorities, customer feedback, team performance, risks, and organizational learning into one leadership tool.

  1. Can a startup use a simple spreadsheet as a scorecard?

Absolutely. Many successful startups begin with a shared spreadsheet or document. The value comes from consistently reviewing the information and using it to guide decisions, not from purchasing expensive reporting software.

References


The Startup CEO’s Weekly Scorecard Read More »

Founder leading a startup planning session using a simple operating system with quarterly goals, documentation, and accountability.

Building Your Startup Operating System Before You Need One

Founder leading a startup planning session using a simple operating system with quarterly goals, documentation, and accountability.
A simple operating system helps startup founders create clarity, improve execution, and prepare for sustainable growth.

Building Your Startup Operating System Before You Need One

One of the biggest myths in entrepreneurship is that startups should avoid structure because structure slows innovation.

In reality, the opposite is true.

The startups that execute consistently are rarely the ones with the best ideas. They’re the ones that make decisions quickly, communicate clearly, and stay focused on what matters most.

That’s exactly what a startup operating system helps you do.

An operating system is not software. It isn’t another app or project management platform. It’s simply the collection of routines, processes, expectations, and decision-making habits that help your business run predictably.

Many founders don’t think about creating one until they have ten or twenty employees and everything feels chaotic. By then, they’re spending more time fixing communication problems than building the company.

The best time to build an operating system is when your team is still small.

For founders with fewer than ten employees, a simple operating system can dramatically improve execution without creating unnecessary bureaucracy.

What Is a Startup Operating System?

Think about your computer.

The operating system doesn’t perform the work for you. Instead, it allows every application to work together efficiently.

Your startup needs the same thing.

A startup operating system provides a consistent framework for how your business operates every day. It answers questions such as:

  • How do we make decisions?
  • How do we prioritize work?
  • How do we communicate?
  • How do we track progress?
  • How do we solve problems?
  • How do we hold each other accountable?

Without clear answers, every decision becomes a discussion. Every meeting becomes longer than necessary. Every employee develops their own way of working.

Eventually, inconsistency becomes expensive.

Fortunately, creating an operating system doesn’t require expensive consultants or enterprise software.

It simply requires discipline.

Why Founders Wait Too Long

In the early stages, founders often believe they can keep everything in their heads.

That works when you’re alone.

It becomes difficult when you hire your first employee.

Then your second.

Then your fifth.

Suddenly, people start asking questions you’ve answered before.

Tasks get duplicated.

Customers receive inconsistent experiences.

Important conversations happen in Slack, email, text messages, and hallway discussions.

Nothing is technically broken.

Everything is simply harder than it should be.

This is usually when founders begin searching for business operating systems like the Entrepreneurial Operating System (EOS), OKRs, or Scaling Up.

These frameworks are excellent, but many startups can benefit from something much simpler long before they need a comprehensive methodology.

Your Meeting Cadence Creates Your Company Rhythm

Meetings often receive a bad reputation because many companies hold meetings without purpose.

The problem isn’t meetings.

The problem is inconsistent communication.

Even a five-person startup benefits from having predictable conversations.

A simple cadence might include:

Weekly Team Meeting

Spend 30 to 45 minutes reviewing priorities, discussing roadblocks, and identifying decisions that need to be made. Keep updates concise and focus on solving problems instead of reporting activity.

Monthly Business Review

Take a step back from day-to-day work and examine your progress. Review financial performance, customer acquisition, sales pipeline, marketing initiatives, product development, and operational challenges.

Quarterly Planning Session

Dedicate several hours to reviewing the previous quarter, identifying lessons learned, setting priorities, and deciding what success should look like over the next 90 days.

Consistency matters more than perfection.

When everyone knows when important conversations will happen, fewer surprises occur throughout the week.

Goals Give Everyone the Same Direction

Startups rarely fail because people work too little.

They fail because people work on different things.

Every founder has experienced the feeling of staying busy while making very little progress.

That’s usually a goal problem.

Instead of creating dozens of objectives, focus on a handful of priorities that genuinely move the business forward.

Ask questions like:

  • What three things must happen this quarter?
  • What metrics will tell us we’re succeeding?
  • Which projects support those goals?
  • Which projects should wait?

Simple goals create clarity.

Clarity creates momentum.

Many successful startups use measurable objectives similar to Objectives and Key Results (OKRs), introduced at Intel and later popularized by Google. Intel Google Even if you don’t formally adopt OKRs, the principle remains valuable: define a small number of ambitious objectives and measure progress with clear, observable outcomes.

Documentation Saves Time Every Week

Documentation feels unnecessary until someone asks the same question for the tenth time.

Founders often believe documentation is only for large corporations.

It’s actually more valuable for startups.

Documenting your work helps new employees onboard faster, reduces mistakes, preserves institutional knowledge, and allows founders to spend less time repeating themselves.

You don’t need a 300-page operations manual.

Start small.

Document:

  • Sales processes, including how leads are qualified, followed up, and moved through the pipeline so every customer receives a consistent experience.
  • Customer onboarding steps that explain exactly what happens after someone becomes a customer, helping eliminate missed tasks and confusion.
  • Marketing workflows that outline how campaigns are planned, reviewed, approved, and measured.
  • Product development processes that clarify how ideas are prioritized, tested, and released.
  • Internal policies such as vacation requests, software access, and expense approvals so employees know where to find answers without asking repeatedly.

Many startups successfully use simple documentation tools like Notion, Confluence, or Google Docs.

The important part isn’t the software.

It’s creating a single source of truth.

Build a Better Decision Making Process

One hidden cost of startup growth is decision fatigue.

Every decision eventually lands on the founder’s desk.

That’s not sustainable.

Instead, create simple rules around decision making.

Examples include:

  • Define which decisions employees can make independently and which require leadership approval. This increases confidence while preventing unnecessary delays.
  • Clarify how customer issues should be escalated so everyone understands when additional support is needed.
  • Establish spending thresholds that determine when purchases need management approval, allowing routine expenses to move quickly while protecting larger investments.
  • Identify which company metrics influence strategic decisions, ensuring discussions are based on data rather than assumptions.

The goal isn’t eliminating founder involvement.

It’s making sure founders spend their time on the highest-value decisions.

Accountability Is About Clarity, Not Control

Many founders avoid accountability because they worry it will create a corporate culture.

Actually, accountability creates trust.

People perform better when expectations are clear.

Accountability should answer four questions:

  • Who owns this?
  • When is it due?
  • How will success be measured?
  • What happens if priorities change?

Ownership should always belong to one person.

Teams contribute.

Individuals own outcomes.

This eliminates confusion and reduces duplicated work.

Quarterly Planning Keeps Everyone Focused

Annual planning is valuable.

Quarterly planning is actionable.

Startups change too quickly to rely solely on yearly goals.

Every 90 days, ask your leadership team:

  • What worked?
  • What didn’t?
  • What should we stop doing?
  • What opportunities have appeared?
  • What three priorities matter most next quarter?

Limiting priorities forces difficult but valuable conversations.

Everything cannot be the highest priority.

Quarterly planning creates a healthy rhythm of reflection, adjustment, and execution.

Many high-growth organizations use 90-day planning because it strikes a balance between long-term vision and short-term adaptability.

A Simple Operating System for Teams Under 10 People

Your startup doesn’t need dozens of processes.

It needs consistency.

A practical operating system might look like this:

Weekly Team Meeting: Review metrics, priorities, roadblocks, and upcoming work in a structured 30 to 45 minute session.

Monthly Review: Examine financial performance, customer feedback, product progress, marketing results, and operational issues. Use this meeting to identify trends rather than react to isolated events.

Quarterly Planning: Set three to five company priorities for the next 90 days, assign clear ownership, and define measurable outcomes.

Shared Documentation: Maintain one central location where employees can find processes, policies, meeting notes, and key decisions.

Visible Scoreboard: Track a handful of metrics such as revenue, customer acquisition, sales pipeline, churn, cash runway, or product milestones. Visibility keeps everyone aligned on what matters most.

Decision Framework: Document who owns which types of decisions so work moves quickly without waiting for founder approval on every issue.

This level of structure supports growth without creating unnecessary overhead.

How GrowthCraft Helps Founders Build Better Businesses

Many first-time founders understand their product better than they understand how to run a growing business.

That’s completely normal.

Building a company requires learning leadership, execution, communication, financial planning, customer development, and operations at the same time.

This is where communities like GrowthCraft can provide significant value.

GrowthCraft focuses on helping early-stage founders develop the practical skills required to build sustainable companies. Through educational resources, experienced mentors, workshops, and a community of fellow entrepreneurs, founders can learn proven operating practices before growth exposes weaknesses.

Instead of waiting until problems become expensive, founders can adopt practical systems early, helping their companies scale with greater confidence and less chaos.

An operating system is not about adding bureaucracy.

It’s about giving your team the structure needed to move faster together.

Final Thoughts

Every successful company develops an operating system.

The only question is whether it’s intentional.

Without one, your company runs on memory, assumptions, and informal conversations.

With one, your business develops repeatable habits that make growth easier.

You don’t need hundreds of employees.

You don’t need complicated software.

You don’t need an expensive consulting engagement.

You simply need consistent ways of communicating, planning, documenting, making decisions, and holding people accountable.

Build those habits while your team is still small, and your future self will spend far less time untangling operational problems.

The best startup operating systems are built before they’re desperately needed.


Frequently Asked Questions

1. What is a startup operating system?

A startup operating system is a collection of processes, meeting rhythms, documentation, goals, and decision-making practices that help a business operate consistently. It provides a framework for execution rather than relying on informal communication.

2. When should a startup implement an operating system?

The ideal time is before your company experiences rapid growth. Even startups with two to five employees benefit from establishing consistent meetings, documentation, accountability, and planning practices early.

3. Is EOS the only operating system startups should use?

No. EOS is one popular framework, but many startups succeed using simpler systems built around regular meetings, quarterly planning, clear goals, documented processes, and accountability. The best operating system is the one your team consistently follows.

4. What tools should startups use to manage their operating system?

Many startups use affordable tools such as Notion for documentation, Google Workspace for collaboration, Trello or Asana for task management, and Slack or Microsoft Teams for communication. The specific software matters less than establishing consistent habits.

5. How can GrowthCraft help first-time founders?

GrowthCraft provides educational content, mentorship, founder communities, workshops, and practical guidance that help entrepreneurs develop the operational skills needed to build scalable businesses. Its focus is on helping founders establish effective business practices before operational challenges slow growth.

References

Building Your Startup Operating System Before You Need One Read More »

Startup founder reviewing business systems and planning priorities to prevent burnout while building a sustainable company.

Founder Burnout Is a Business Problem, Not a Personal Problem

Startup founder reviewing business systems and planning priorities to prevent burnout while building a sustainable company.
Founder burnout is often caused by business systems that rely too heavily on one person. Building repeatable processes creates healthier companies.

Founder Burnout Is a Business Problem, Not a Personal Problem

When most people picture a startup founder, they imagine someone working late nights, answering emails at midnight, skipping vacations, and sacrificing nearly everything to build a company. Society often celebrates this image as proof of commitment and determination.

Unfortunately, this mindset has also contributed to one of the most common reasons startups fail.

Founder burnout.

Burnout is often treated as a personal issue. Founders are told they need better work-life balance, more sleep, better exercise habits, or improved stress management. While those things certainly matter, they miss the bigger picture.

Burnout is usually the result of how a business is designed and operated.

If every decision depends on one person, if every customer problem lands on the founder’s desk, and if every process exists only inside the founder’s head, the company itself creates burnout.

That makes burnout a business problem.

For first-time founders, recognizing this distinction is incredibly important. The goal is not simply to survive another week. The goal is to build a company that can continue growing without requiring the founder to carry every responsibility forever.

This article explores why founder burnout happens, how to recognize it early, and the practical systems every startup should build to avoid becoming another burnout statistic.

Why Founder Burnout Kills Startups

Most startups begin with one person doing nearly everything.

Sales.
Marketing.
Product development.
Customer support.
Finance.
Operations.
Fundraising.

At first, this makes sense. Resources are limited, budgets are small, and hiring is often impossible.

The problem begins when the company starts growing but the founder never changes how work gets done.

Instead of building systems, founders simply work harder.

Instead of documenting processes, they memorize everything.

Instead of delegating decisions, they become the bottleneck.

Eventually, every important activity depends on one exhausted individual.

Research continues to show that founder mental health challenges are widespread. A study by the National Institute of Mental Health highlights the relationship between chronic stress and impaired decision making. Similarly, the Harvard Business Review has published multiple studies showing that sustained overload significantly reduces strategic thinking, creativity, and leadership effectiveness.

For startups, these consequences become expensive.

Burned-out founders often experience:

  • Slower decision making because every choice feels overwhelming rather than exciting.
  • Reduced creativity, making it harder to solve customer problems or identify new opportunities.
  • Poor communication with investors, employees, and customers.
  • Delayed product improvements because priorities constantly shift.
  • Lower team morale because stress spreads throughout the organization.

Burnout rarely appears overnight.

It usually builds slowly while the business continues operating.

By the time founders realize something is wrong, many opportunities have already been missed.

Early Warning Signs

Many founders mistake burnout for being “busy.”

Being busy is temporary.

Burnout is different.

Burnout changes how you think, make decisions, and interact with your business.

Some of the earliest warning signs include consistently avoiding important work because everything feels equally urgent. Instead of focusing on strategic priorities, founders spend their days reacting to emails, Slack messages, customer requests, and emergencies.

Another warning sign is decision fatigue.

Simple decisions begin taking much longer than they should.

Choosing between two vendors suddenly feels exhausting.

Responding to customer feedback becomes emotionally draining.

Even scheduling meetings feels like another impossible task.

Burnout also affects relationships.

Founders may become less patient with employees, customers, advisors, or family members. Communication becomes shorter, frustration increases, and collaboration suffers.

Perhaps the biggest warning sign is losing enthusiasm for work that once felt exciting.

Building a startup will always involve difficult days.

But if every day feels heavy for weeks or months, the business itself probably needs attention.

Delegation Versus Doing Everything Yourself

Many founders believe nobody can perform a task as well as they can.

Sometimes that is true.

Most of the time, it is not.

The bigger issue is whether the founder should be performing that task in the first place.

Successful founders gradually shift from doing work to designing work.

That means creating repeatable processes that others can execute consistently.

Delegation is not simply assigning tasks.

Effective delegation requires three things.

First, clearly define the desired outcome. Team members need to understand what success looks like rather than simply receiving instructions.

Second, document the process whenever possible. Even a simple checklist can eliminate confusion and reduce repeated questions.

Third, establish decision boundaries. Employees should know which decisions they can make independently and when they should involve leadership.

Delegation often feels slower initially because teaching someone takes time.

However, every hour invested in training eventually returns many hours of founder capacity.

Think of delegation as building an asset.

Each documented process becomes something the company owns rather than something only the founder knows.

Building Systems Before Hiring

Many founders assume hiring solves burnout.

It often does not.

Hiring without systems simply transfers chaos to more people.

Imagine hiring your first sales representative without documented pricing, qualification criteria, customer messaging, or CRM processes.

Instead of reducing workload, the founder now spends every day answering questions.

The employee becomes dependent rather than productive.

Before hiring, startups should identify recurring activities that happen every week.

These might include:

Every customer onboarding meeting should follow the same sequence.

Marketing content should follow a documented approval process.

Customer support requests should include standard response procedures.

Sales follow-up should have defined timelines and templates.

Financial reporting should occur on the same schedule each month.

None of these systems need to be complicated.

Simple documents stored in shared folders often provide enough structure for early-stage companies.

The objective is consistency.

When work becomes predictable, scaling becomes easier.

Creating Founder Operating Rhythms

One overlooked cause of burnout is constantly changing priorities.

Without structure, founders spend every day reacting.

Successful CEOs create operating rhythms that reduce unnecessary decision making.

An operating rhythm is simply a consistent schedule for recurring leadership activities.

For example:

Monday might focus on company planning and reviewing key metrics.

Tuesday could be dedicated to customer meetings.

Wednesday might become product development time.

Thursday could focus on partnerships or fundraising.

Friday becomes review, documentation, and preparation for the following week.

This structure creates mental clarity.

Instead of asking, “What should I work on today?” founders already know.

Operating rhythms also improve communication.

Employees understand when decisions are made, meetings occur, and priorities are reviewed.

Consistency reduces uncertainty across the entire company.

The Society for Human Resource Management (SHRM) has also noted that predictable work structures reduce workplace stress while improving productivity and engagement.

Weekly CEO Checklist

Every founder should schedule time each week to step away from daily tasks and evaluate the business itself.

A simple weekly CEO checklist might include:

Review Key Metrics

Look beyond revenue. Examine customer acquisition, retention, cash flow, sales pipeline activity, product usage, and customer satisfaction. Trends often matter more than individual numbers.

Evaluate Bottlenecks

Identify which decisions required founder involvement this week. Ask whether any could become documented processes or delegated responsibilities.

Talk to Customers

Spend time understanding customer experiences directly. Founders should remain connected to real problems even as the company grows.

Review Team Priorities

Ensure everyone understands the week’s objectives. Misalignment creates unnecessary work and increases stress throughout the organization.

Protect Strategic Thinking Time

Reserve uninterrupted time each week to think about long-term direction instead of immediate tasks. This often becomes the highest-value activity on the calendar.

Reflect Personally

Ask simple questions.

What gave me energy this week?

What drained my energy?

What should I stop doing?

The answers often reveal where systems need improvement.

How GrowthCraft Helps Founders Avoid Burnout

Many founders believe they need more motivation.

What they actually need is better structure.

This is where GrowthCraft makes a meaningful difference.

GrowthCraft was created specifically to help early-stage founders navigate the challenges of building companies without feeling isolated or overwhelmed.

Rather than simply offering educational content, GrowthCraft provides practical guidance, experienced mentors, collaborative communities, and proven startup frameworks that help founders make better decisions earlier.

Members gain access to resources covering business planning, customer validation, financial readiness, fundraising preparation, operational planning, and leadership development.

More importantly, founders gain access to people who have experienced similar challenges.

Many startup problems feel unique until founders discover others have already solved them.

GrowthCraft helps founders avoid common mistakes before they become expensive setbacks.

By building stronger operating systems early, founders spend less time fighting daily fires and more time creating sustainable businesses.

Burnout prevention is not about working fewer hours.

It is about building companies that no longer require one person to do everything.

That is exactly the type of long-term thinking GrowthCraft encourages.

Final Thoughts

Every startup demands hard work.

There will always be long days, difficult decisions, and periods of uncertainty.

But constant exhaustion should never become the operating model.

If your company only functions because you never stop working, your business has a systems problem, not a motivation problem.

The earlier founders recognize this reality, the easier it becomes to build processes, delegate responsibilities, establish routines, and create sustainable growth.

The strongest startups are not built by founders who can endure the most stress.

They are built by founders who create businesses that can thrive without depending on constant personal sacrifice.

Invest in systems.

Protect your decision-making capacity.

Build operating rhythms.

Ask for help before you need it.

Most importantly, remember that taking care of the business includes taking care of the person leading it.

GrowthCraft exists to help founders do both.


Frequently Asked Questions

1. What causes founder burnout?

Founder burnout usually results from prolonged stress combined with unclear priorities, constant decision making, lack of delegation, and businesses that depend too heavily on one individual. It is often a symptom of operational problems rather than personal weakness.

2. How can founders prevent burnout?

Founders can reduce burnout by documenting processes, delegating responsibilities, creating consistent weekly operating rhythms, tracking meaningful business metrics, and seeking mentorship before problems become overwhelming.

3. Is burnout common among startup founders?

Yes. Multiple studies have shown that entrepreneurs experience significantly higher levels of stress, anxiety, and burnout than many other professions because they often carry responsibility for employees, customers, investors, and financial outcomes simultaneously.

4. Should founders hire more people to reduce burnout?

Not immediately. Hiring without clear systems often creates additional management work. Startups should first document recurring processes so new employees can contribute effectively from the beginning.

5. How does GrowthCraft help prevent founder burnout?

GrowthCraft provides founders with educational resources, experienced mentors, practical startup frameworks, collaborative communities, and strategic guidance that help founders build sustainable companies with stronger operating systems and healthier leadership practices.


References and Sources

Founder Burnout Is a Business Problem, Not a Personal Problem Read More »

Scroll to Top