GrowthCraft

startup financial projections

Early-stage startup founders reviewing financial projections and funding-readiness metrics before meeting with investors

How to Know If Your Startup Is Actually Ready to Raise Money

How to Know If Your Startup Is Actually Ready to Raise Money

Early-stage startup founders reviewing financial projections and funding-readiness metrics before meeting with investors
Before raising capital, founders should understand their customers, market, financials, business model, and the specific milestones funding will help achieve.

How to Know If Your Startup Is Actually Ready to Raise Money

Raising money can feel like the next obvious step for a startup. You have an idea, you have built something, you may have early customers, and now you need capital to move faster.

But needing money and being ready to raise money are not the same thing.

For an early-stage founder, one of the most important funding decisions is knowing whether outside capital will actually help the company reach its next meaningful milestone. Investors are not simply looking for startups that need cash. They are looking for evidence that additional capital can help a promising business become more valuable.

That distinction is at the heart of funding readiness.

The U.S. Securities and Exchange Commission specifically recommends that companies consider their capitalization table, financials, funding requirements, use of proceeds, investor strategy, advisors, and long-term vision before beginning a capital raise. The Small Business Administration similarly points to market research, financial projections, management capability, and due diligence as important parts of preparing for outside funding.

For first-time founders, the better question is not, “How do I raise money?”

It is, “What would make an investor believe that putting money into my company today is likely to produce a meaningful result tomorrow?”

Funding Is a Tool, Not the Goal

One of the easiest mistakes for a startup founder to make is treating fundraising as a milestone in itself.

Raising $500,000 does not mean the startup is successful. Raising $2 million does not mean the business has found product-market fit. Funding simply gives the company additional resources.

The real purpose of funding should be tied to a specific business outcome.

Perhaps you need capital to finish development of a product, hire the people required to deliver it, conduct a larger market test, expand customer acquisition, complete regulatory work, or reach a revenue milestone. Whatever the reason, you should be able to explain what the money will accomplish.

The SEC recommends that founders calculate their runway and have a clear plan for how the proceeds will be used.

A useful test is this:

If an investor gave you the money tomorrow, what would be measurably different about your company 12 to 18 months from now?

If you cannot answer that question, you may not be ready to raise.

Why Raising Money Too Early Can Hurt a Startup

More money does not automatically solve startup problems.

In fact, raising money before you understand your customer, business model, or market can make existing problems more expensive.

Suppose you raise $1 million before you know exactly who your best customer is. You now have money to hire employees, build features, spend on marketing, and increase operating expenses. But if the underlying customer assumptions are wrong, you can spend $1 million discovering what you could have learned for $50,000.

Early funding can also create pressure to grow before the company is ready. Investors expect progress. Employees are hired. Expenses increase. Expectations change. The founder can end up managing a larger organization before the basic business has been validated.

This does not mean founders should always wait until they are profitable or have significant revenue. Some startups need capital very early because they have substantial research, development, regulatory, manufacturing, or infrastructure requirements.

The question is whether you have enough evidence to justify the amount of capital you are seeking and whether the capital has a clearly defined job.

The Questions Investors Will Ask

You should be able to answer the basic investor questions before you start pitching.

Y Combinator’s seed fundraising guidance provides a useful framework that includes the problem, customer, solution, market, competition, traction, business model, team, and fundraising requirements.

Those questions generally come down to five areas:

  • Why this problem? Can you demonstrate that the problem is real, important, and painful enough for customers to address?
  • Why this solution? What have you built, and why is it meaningfully better, faster, cheaper, easier, or more valuable than existing alternatives?
  • Why this market? How large is the opportunity, and what evidence supports your market assumptions?
  • Why your company? Why are you and your team particularly qualified to solve this problem?
  • Why now and why funding? What has changed, what have you learned, and what will additional capital allow you to accomplish?

You do not need to have perfect answers. Early-stage companies rarely do. You do need to understand what you know, what you do not know, and what evidence supports your assumptions.

Evidence of Customer Demand

Customer demand is one of the strongest indicators of funding readiness.

That does not necessarily mean you need millions of dollars in revenue. Depending on the stage and type of company, useful evidence could include paying customers, signed contracts, pilot customers, repeat usage, preorders, strong customer retention, partnerships, letters of intent, or measurable engagement.

The important distinction is between what people say and what people do.

Someone telling you, “That’s a great idea,” is encouraging.

Someone agreeing to pay for it is much stronger evidence.

Techstars similarly emphasizes traction and evidence that customers want the product as important elements of a compelling investment case.

Before approaching investors, ask yourself:

  • Who has actually used the product?
  • Who has paid for it?
  • Who has used it more than once?
  • What percentage of customers continue using it?
  • What problem caused them to buy?
  • Why did customers choose you instead of an alternative?
  • What have customers asked you to improve?

Your answers create a much stronger story than a collection of assumptions.

Business Model Clarity

Investors need to understand how the company eventually makes money.

Your business model does not have to be perfect. It does need to be understandable.

Can you explain who pays, what they pay for, how much they pay, how frequently they pay, and what it costs you to deliver the product or service?

If your current model is expected to change, explain why.

A founder who says, “We haven’t figured out monetization yet,” may be describing a legitimate early-stage reality. But the founder should also be able to explain what has been tested and what needs to be learned next.

A strong early business model conversation might sound like this:

“We currently charge X for Y. We tested three pricing approaches with 20 customers. This option produced the strongest conversion and retention. We believe we can improve gross margins as volume increases.”

That demonstrates learning rather than pretending certainty.

Financial Understanding

You do not need to be an accountant to raise money.

You do need to understand your company’s financial reality.

At minimum, you should know your current cash balance, monthly expenses, cash burn, runway, revenue, gross margin if applicable, major cost categories, and the assumptions behind your financial projections.

You should also know exactly how much you are asking for and why.

The SEC specifically identifies financial statements, capitalization tables, runway, and a clear plan for the use of proceeds as important components of capital-raising preparation.

Your financial model should not exist simply because an investor expects to see a spreadsheet. It should help you make decisions.

For example, if you are raising $750,000, what does that money allow you to accomplish that $300,000 would not? What happens if you raise $1 million? What happens if you raise only $500,000?

Understanding these scenarios makes you a better capital allocator and a more credible founder.

The U.S. Small Business Administration’s business planning guidance (https://www.sba.gov/counseling/plan-your-business/) also recommends connecting funding requirements with financial projections and explaining the assumptions behind those projections.

Market Opportunity

A great product in a tiny or shrinking market may not produce the type of return some investors are looking for.

That does not mean every startup needs to claim a massive market. It means you need to understand the market you are entering.

Start with the actual customer.

How many potential customers exist? What do they currently spend to solve the problem? What alternatives are available? How competitive is the market? What trends could increase or decrease demand?

The SBA recommends examining demand, market size, pricing, competition, customer characteristics, and broader economic factors when conducting market research.

Be careful with the common “1% of a $10 billion market” argument. Investors generally need more than a large theoretical market number. They need to understand how your company can realistically capture a meaningful portion of that opportunity.

Founder and Team Readiness

At the earliest stages, investors are investing heavily in the people.

That does not mean you need a large team.

It means the people involved need to make sense for the company’s current stage and future challenges.

Who owns the technical work? Who understands customers? Who handles operations? Who is responsible for sales? What capabilities are missing?

If there is a major gap, acknowledge it.

A founder who understands the company’s weaknesses is often more credible than one who claims the team can do everything.

Research discussed in Harvard Business Review also highlights the importance investors place on startup teams during due diligence, alongside business model, market opportunity, and growth plans.

Legal and IP Considerations

Legal preparation is easy to overlook when you are focused on building the product.

It can become a serious problem during due diligence.

Before raising capital, you should know who owns the company, how equity is divided, whether founder agreements are documented, whether intellectual property belongs to the company, and whether important contracts are in place.

If contractors or employees created important technology, make sure the company has appropriate agreements addressing intellectual property ownership.

If your company relies on patents, trademarks, copyrights, proprietary technology, trade secrets, or other intellectual property, understand what has been protected and what remains exposed.

The SBA specifically identifies intellectual property plans, patents, legal documents, licenses, permits, contracts, and other supporting materials as information that may belong in a company’s funding documentation.

The SEC also recommends having experienced legal and accounting advisors involved in the capital-raising process.

This is an area where professional legal advice is particularly important. Securities laws can apply when a company sells equity or other securities, and the appropriate exemption and compliance requirements depend on the circumstances. The SEC provides current educational resources on exempt offerings and capital raising.

What Should Be Prepared Before Approaching Investors?

You do not need a giant data room before having your first investor conversation. You should, however, be prepared to support the story you are telling.

At a minimum, consider preparing:

A clear pitch deck. It should explain the problem, customer, solution, market, traction, business model, team, competitive landscape, and funding request. Y Combinator’s seed fundraising framework provides a useful starting structure.

A financial model. Your model should show historical performance where available, projected revenue and expenses, cash requirements, and the assumptions behind your projections.

A capitalization table. Know exactly who owns what before inviting new investors into the company.

Customer evidence. Organize your strongest evidence of demand, including revenue, customer growth, retention, pilots, contracts, partnerships, testimonials, or other meaningful indicators.

A use-of-funds plan. Explain where the money will go and what business milestones those expenditures are intended to produce.

A due diligence folder. Organize important corporate, financial, legal, intellectual property, customer, employee, and contractual documents so you can respond efficiently when investors begin asking questions.

The SBA describes due diligence as a process in which investors may examine management, markets, products and services, corporate governance documents, and financial statements.

A Practical Funding-Readiness Checklist

Before actively raising money, give yourself one point for every statement you can confidently answer “yes” to:

1. I can clearly explain the customer problem. I can identify the specific customer experiencing it and explain why the problem matters.

2. I have evidence that customers want the solution. I have more than opinions or survey responses. I have meaningful evidence such as usage, revenue, pilots, contracts, or other customer behavior.

3. I understand my business model. I know who pays, what they pay for, how much they pay, and how the economics are expected to work.

4. I understand my numbers. I know my cash position, burn rate, runway, revenue, major expenses, and key financial assumptions.

5. I understand my market. I can explain my target market, competitors, customer alternatives, market size, and why the opportunity can grow.

6. I know what the funding will accomplish. I can connect the amount I am raising to specific milestones rather than simply saying I need money to grow.

7. My team can execute the next stage. I know the team’s strengths and the important capabilities we still need.

8. My ownership and legal structure are organized. My cap table, corporate records, founder agreements, contracts, and IP ownership are reasonably prepared.

9. I know which investors I should approach. I am targeting investors whose stage, industry interests, geography, check size, and expertise fit my company.

10. I can explain what happens if I do not raise. I understand my alternatives and what the company can accomplish with its existing resources.

If you cannot check most of these boxes, that does not mean your startup is failing.

It means you have identified the work that should happen before the fundraising process becomes the primary focus.

GrowthCraft’s Role in Funding Readiness

This is where funding readiness fits into the broader work GrowthCraft provides for early-stage, first-time founders.

GrowthCraft’s approach is not simply about helping a founder create a pitch deck and start asking investors for money. The more important question is whether the company is ready for the scrutiny that comes with outside capital.

That means looking at the business as a whole: the customer and market, business model, financial structure, legal protection, operating priorities, and founder decision-making.

GrowthCraft can serve as a resource for founders working through those questions before they begin a serious fundraising process. The goal is not to make every startup investor-ready immediately. The goal is to help founders understand what needs to be true before outside capital is likely to create meaningful value.

Sometimes the right answer is to raise money now.

Sometimes the right answer is to spend the next six months proving customer demand, refining the business model, cleaning up the financials, protecting intellectual property, or reaching a specific operating milestone first.

Knowing the difference is part of being ready.

Final Thought: Raise Money Because You Are Ready to Use It

The strongest reason to raise startup funding is not that your bank account is getting low.

It is that you have learned enough about your business to know what additional capital can accomplish.

You understand the customer. You have evidence of demand. You know how the business can make money. You understand the market. You know your numbers. Your team is capable of executing the next stage. Your legal and ownership structure can withstand due diligence. Most importantly, you have a specific reason that additional capital should make the company substantially stronger.

Fundraising is not a substitute for figuring out the business.

It is a tool for accelerating a business that is beginning to demonstrate that it works.

For an early-stage founder, that distinction can save time, money, ownership, and a great deal of frustration.

Frequently Asked Questions

How much revenue does a startup need before raising money?

There is no universal revenue threshold for raising startup funding. Some startups raise before generating revenue because they require substantial development, research, regulatory work, or other upfront investment. The more important question is whether you have credible evidence supporting your assumptions and a clear reason why additional capital is needed now.

Should I raise money before I have product-market fit?

Sometimes. Early-stage investors may fund companies before product-market fit if the opportunity, team, technology, market, and early evidence are compelling. However, raising substantial capital before understanding your customer can increase the cost of experimentation. Founders should be clear about what they have validated and what they still need to learn.

What financial information do investors expect?

Investors will typically want to understand your current financial position, ownership structure, revenue and expenses where applicable, cash burn, runway, financial projections, and how you intend to use the funding. The SEC specifically identifies financial statements, capitalization tables, runway calculations, and use-of-proceeds plans as important capital-raising preparation.

Do I need a pitch deck before talking to investors?

A formal pitch deck is not necessarily required for every early conversation, but you should be able to clearly explain your problem, customer, solution, market, traction, business model, team, and funding requirements. Once you begin a formal fundraising process, a well-structured deck becomes an important communication tool.

What should I do if my startup is not ready to raise money?

Turn the gaps into milestones. If customer demand is weak, focus on customer validation. If the business model is unclear, test pricing and purchasing behavior. If the financial model is weak, build a realistic cash-flow forecast. If your legal or IP structure is incomplete, address it before due diligence. Being “not ready” is useful information when you know exactly what needs to change.

Recommended Source Materials

For readers who want to go deeper, these are strong reference resources:

How to Know If Your Startup Is Actually Ready to Raise Money Read More »
Early-stage startup founders reviewing a pitch deck, financial projections, and business plans around a conference table.

The Best Pitch Deck Outline: A Step-by-Step Guide for First-Time Startup Founders

Early-stage startup founders reviewing a pitch deck, financial projections, and business plans around a conference table.
A clear pitch deck helps startup founders communicate their business opportunity, demonstrate progress, and explain their funding needs.

The Best Pitch Deck Outline: A Step-by-Step Guide for First-Time Startup Founders

A great pitch deck does more than explain what your startup does. It tells a compelling story about a problem worth solving, a business worth building, and a team capable of making it happen.

For early-stage, first-time startup founders, creating that story can feel overwhelming. What should you include? How much financial detail is enough? How do you demonstrate that your idea has potential when you are still developing the product or finding your first customers?

The good news is that you do not need 30 slides filled with complicated charts and financial projections. A focused, well-structured pitch deck can communicate your opportunity in 10 to 12 slides.

Think of your pitch deck like a movie trailer. It should introduce the opportunity, build interest, demonstrate why your solution matters, and leave investors wanting to learn more. It is not meant to tell your entire business story. It is meant to earn the next conversation.

This guide walks you through the best pitch deck outline, explains what belongs on each slide, and provides actionable advice for turning your startup idea into a clear, credible presentation.

What Is a Startup Pitch Deck?

A startup pitch deck is a concise presentation that explains your business opportunity to potential investors, partners, or other stakeholders. It typically covers the problem, solution, product, market, business model, competition, traction, team, and financial needs.

Although pitch decks are often associated with fundraising, the process of creating one is also valuable for founders who are not yet ready to raise money. It forces you to clarify your assumptions, identify what you still need to learn, and explain why your business deserves attention.

Successful startups such as Airbnb and Uber have used investor presentations to communicate their business opportunities. Their original decks are useful examples of how founders can explain a business model, market opportunity, and customer need in a relatively compact format. However, there is no single universally successful deck template. Your presentation should reflect your company’s stage, business model, and fundraising objectives.

For most early-stage startups, a 10-slide core presentation is a practical starting point. You can expand it to 12 slides when your team, product, or financial information deserves additional attention.

The Core 10-Slide Pitch Deck Outline

The following outline combines the familiar 10-slide structure with the practical details founders need to explain their product, demonstrate traction, and make a clear funding request. It follows the broad logic of Sequoia Capital’s business-planning and pitching guidance, with additional slides and detail to suit an early-stage fundraising conversation.

Slide 1 – Introduction / Cover

1. Introduction: What does your company do?

Your opening slide should make it immediately clear who you are and what your company does. Include your company name, logo, and a concise, one-sentence description of the value you provide.

Avoid vague statements such as “Revolutionizing the future of business.” Instead, explain what you do in language a potential customer or investor can understand. For example, a home-sharing startup might say, “We help travelers find places to stay with local hosts.”

Actionable tip: Complete this sentence: “We help \(specific customer\) solve \(specific problem\) by \(your approach\).” Use it as a starting point for your tagline. Your opening should establish context, not require the investor to guess what the business is.

Slide 2 – The Problem

2. The Problem: What needs to change?

Investors need to understand the customer pain your business is addressing. Identify the specific people or organizations experiencing the problem, explain what makes it difficult, and show why existing ways of dealing with it fall short.

Use evidence whenever possible. Customer interviews, survey results, industry research, operational data, or a short customer story can help establish that the problem is real. For a business-to-business startup, you might explain how a manual process creates delays, increases costs, or limits a company’s ability to serve customers.

Do not simply claim that “everyone has this problem.” Define the target customer and explain how frequently the problem occurs, how serious it is, and what it costs in time, money, or missed opportunities.

Actionable tip: Speak with potential customers and document their actual experiences. Separate what they told you from what you believe is happening. A specific, well-supported problem is more useful than a dramatic but unsubstantiated claim.

Slide 3 -The Solution

3. The Solution: How do you solve the problem?

Introduce your product or service as the direct response to the problem on the previous slide. Explain what changes for the customer when they use your solution and why your approach is meaningfully different from the alternatives.

Keep the explanation focused on the primary benefit. A long list of features can make it difficult to understand the central value proposition. Instead, describe the key action your product enables and the outcome it is designed to deliver.

For example, rather than saying, “Our platform includes automation, reporting, and AI-powered analytics,” explain how the platform helps a particular customer complete a time-consuming task with less manual work.

Actionable tip: Write one sentence that connects the problem directly to your solution. If the relationship is not obvious, revisit the problem statement or simplify the solution explanation.

Slide 4 – Product / Demo

4. Product / Demo: What does it look like in action?

Give investors a tangible understanding of what you are building. A clear screenshot, prototype, short demonstration, or simple workflow diagram can help turn an abstract idea into something they can see and understand.

Focus on the primary use case. Show how a customer begins, what they do with your product, and what result they receive. You do not need to demonstrate every feature. Choose the part of the experience that best illustrates your value proposition.

If your product is still being developed, be transparent. Label conceptual screens as mockups and explain what is already built, what is being tested, and what remains to be completed.

Actionable tip: Prepare a short, reliable demonstration that can be understood without a lengthy technical explanation. Keep a backup screenshot or recorded demo available in case your live presentation encounters technical problems.

Slide 5 – Market Size

5. Market Size: How large could this opportunity become?

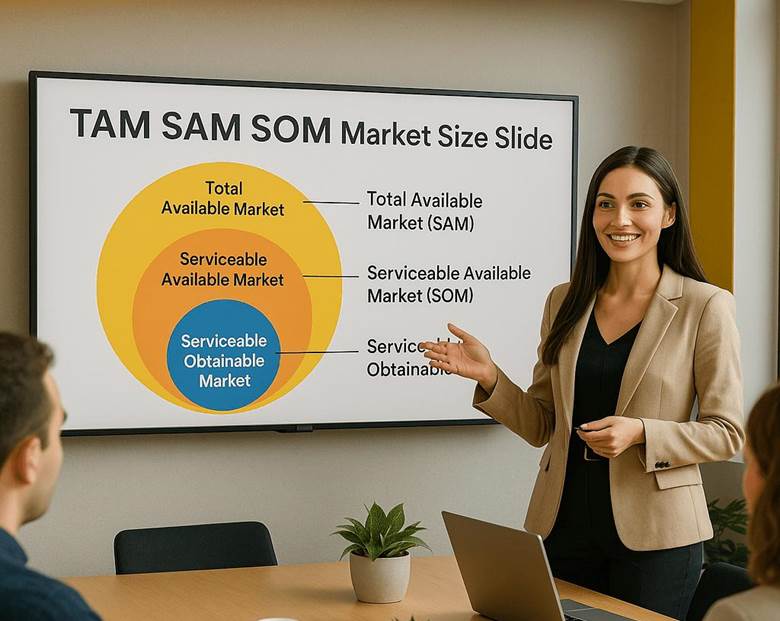
Investors need to understand whether your startup is addressing a sufficiently meaningful market and which portion you can realistically serve. The common framework uses three related measures: TAM, SAM, and SOM.

TAM: Total Addressable Market

The total demand or revenue opportunity if your product or service could serve the entire relevant market.

SAM: Serviceable Available Market

The portion of that market your business model, product, geography, and target customer definition allow you to serve.

SOM: Serviceable Obtainable Market

The portion of the SAM you believe you can realistically capture over a defined period, considering competition, resources, and execution.

A large market number by itself does not establish a viable business. Explain how you calculated your estimates and what assumptions support them. A bottom-up calculation, such as the number of potential customers multiplied by a defensible annual revenue per customer, can make the opportunity easier to evaluate.

Actionable tip: Identify your initial ideal customer profile, estimate how many such customers exist in your reachable market, and explain how you arrived at the numbers. Cite the underlying data and clearly label estimates as estimates.

Slide 6 – Business Model

6. Business Model: How will your startup make money?

Explain who pays you, what they pay for, and how often revenue is generated. Your model might involve monthly subscriptions, annual contracts, transaction fees, licensing, usage-based pricing, or one-time purchases.

Keep the explanation simple enough that someone unfamiliar with your industry can follow it. If you charge a monthly subscription, show the price or pricing range, who buys it, and what the customer receives. If your business depends on transactions, explain how you earn revenue from each transaction.

Where you have reliable information, introduce basic unit economics. These may include customer acquisition cost, average revenue per customer, gross margin, retention, and customer lifetime value. At the earliest stages, these figures may be assumptions rather than established metrics. Label them accordingly.

Actionable tip: Build a simple model showing how one customer generates revenue and what it costs to serve that customer. Explain what you still need to validate before assuming the model can scale.

Slide 7 – Why Now?

7. Why Now? What makes this the right time?

Explain what has changed to make your solution possible, necessary, or commercially relevant now. This could be a new technology, a change in customer behavior, a regulatory development, lower operating costs, or a shift in the way businesses work.

The goal is to connect a real market change to your specific opportunity. For example, if a new technology makes a previously expensive process affordable, explain how that changes the economics for your target customer.

Avoid relying on broad statements such as “AI is growing” or “digital transformation is accelerating.” Those statements do not explain why your particular business has an opportunity today.

Actionable tip: Identify one or two specific changes, provide credible evidence for them, and explain how each affects customer demand, product feasibility, or your ability to compete. If your timing argument is weak, investigate whether the customer problem or business model needs further validation.

Slide 8 – Competition

8. Competition: What alternatives do customers have?

Every startup competes with something, even if no other company offers the exact same product. Customers may use an established competitor, a different type of software, an outside service provider, an internal process, or simply continue doing nothing.

Identify the alternatives your target customers actually consider. Compare the factors that matter to them, such as price, ease of use, implementation time, capabilities, or customer support. Then explain where your approach differs and why that difference matters.

A comparison matrix can make this information easier to digest but avoid giving yourself an automatic checkmark in every category. Unsupported claims of superiority can undermine the credibility of the entire presentation.

Actionable tip: Ask potential customers what they use today and why. Include direct competitors and the status quo. Explain your current advantage and distinguish it from advantages you hope to develop in the future.

Slide 9 – Traction

9. Traction: What evidence shows that your startup is progressing?

Traction is evidence that your startup is making progress toward building a viable business. For a company with paying customers, this might include revenue growth, customer retention, repeat purchases, or expansion within existing accounts.

For an idea-stage or pre-revenue startup, traction can take other forms. You might show completed customer interviews, prototype testing, letters of intent, pilot commitments, waitlist activity, or measurable progress in product development. The important thing is to explain what the evidence actually demonstrates.

Distinguish between interest and commitment. Someone joining a waitlist is not the same as someone paying for a product. A positive interview is not the same as a signed customer agreement. Investors need to understand the difference.

Actionable tip: Select a small number of meaningful metrics, show how they have changed over time, and state the period covered. Include definitions and avoid mixing different types of evidence into a single growth figure.

Slide 10 – The Ask & Financials

10. The Ask & Financials: What do you need, and what will it accomplish?

Finish your core presentation by stating what you are asking investors to provide and what you intend to accomplish with that support. If you are raising capital, specify the amount, the type of financing if known, and the milestones the funding is expected to support.

Explain how much runway the raise is designed to provide, based on your planned spending and assumptions. Then identify the three major milestones you expect to achieve. These might include launching a commercial product, reaching a defined number of paying customers, or completing a technical validation.

Include a simple three-year financial forecast showing expected revenue, major expenses, and cash needs. Your projections should connect to your customer acquisition assumptions, pricing, hiring plans, and other operating drivers. Avoid presenting speculative revenue growth as if it were guaranteed.

Actionable tip: Make sure the numbers agree across your deck. The amount you are raising, expected monthly spending, runway, hiring plan, and milestones should tell one consistent story. Be prepared to explain the assumptions behind your forecast and what you would change if results are slower than expected.

Two Optional Slides Worth Considering

The 10-slide outline is a starting point, not a rule. Depending on your company’s stage and the story you need to tell, two additional slides can make the presentation more complete.

Optional Slide 11: The Team

Investors are evaluating not just the opportunity, but also the people working to make it happen. Introduce the founders and key team members, emphasizing relevant experience, technical knowledge, industry relationships, or previous accomplishments that connect directly to the business.

For a first-time founder, a lack of previous startup experience does not mean you have nothing to show. Relevant customer knowledge, a working prototype, industry expertise, and the ability to learn quickly can all help explain why you are positioned to pursue the opportunity.

If you have advisors, explain their actual contributions. An advisor who has helped validate your market or establish important industry relationships is more meaningful than a list of impressive names without context.

Optional Slide 12: Vision and Milestones

Close with a clear picture of what the company could become if the strategy works. Explain the larger opportunity beyond your initial product or customer segment, while connecting that future to the practical milestones you need to achieve first.

For example, a startup might begin by solving one workflow problem for a specific type of customer, then expand into adjacent workflows or customer segments after validating demand.

Your vision should communicate ambition without replacing the evidence and execution plan presented in the rest of the deck.

How to Make Your Pitch Deck More Effective – A well-structured deck is only the beginning. How you communicate the information can determine whether investors understand your opportunity.

Tell one connected story – Each slide should build on the previous one. The problem establishes why something needs to change. The solution explains what you propose to do. The product demonstrates how it works. The market and business model explain the opportunity, while traction and financials help establish what you have accomplished and what you need next.

If your slides feel like unrelated sections of a business plan, revisit the narrative. Your goal is to make the connection between customer need, business opportunity, and execution clear.

Use evidence instead of unsupported claims – Whenever possible, support important statements with customer feedback, research, product results, financial data, or other credible evidence. Identify the source and time period for key statistics.

Be especially careful with market size, customer demand, competitive advantages, and financial forecasts. Clearly distinguish what you know, what you estimate, and what you still need to validate.

Make every slide easy to understand – Use a clear headline, one primary message, and visuals that support that message. Avoid filling slides with paragraphs of tiny text or complicated charts that require lengthy explanations.

A useful editing exercise is to read only the slide headlines. They should communicate the basic story of your startup from beginning to end.

Adapt the deck to your company’s stage – An idea-stage startup will not have the same evidence as a company with recurring revenue and established customers. That is expected.

An early-stage founder can focus on customer discovery, the problem’s significance, product validation, market assumptions, and the milestones required to move forward. A startup with customers can provide more detail on revenue, retention, acquisition costs, and repeatable growth.

The important thing is to present the evidence you actually have, rather than trying to make your startup look more mature than it is.

How GrowthCraft Can Help You Build a Better Pitch Deck

Creating a pitch deck is not simply a presentation-design exercise. It requires decisions about your customer, market, product, business model, financial assumptions, and growth strategy.

For a first-time founder, those decisions can be difficult to evaluate independently. You may understand your technology extremely well but need help explaining its commercial value. Or you may have a compelling customer problem but still need to validate the market size, pricing, and path to revenue.

This is where GrowthCraft can serve as a resource.

GrowthCraft supports early-stage founders as they work through the interconnected parts of building a business, including business growth, market fit, financial structure, and legal protection. Its approach to founder education, advisor support, and peer learning can help founders develop the thinking behind their pitch, not just the slides themselves.

Through access to advisors with different areas of expertise, founders can get perspectives on questions such as:

  • Market and customer validation: Are you solving a meaningful problem for a clearly defined customer, and what evidence supports that conclusion?
  • Business model: Does your pricing and revenue model make sense for the customer and the way you plan to operate?
  • Financial planning: Are your spending assumptions, runway, and milestones consistent with your fundraising request?
  • Sales and marketing: Can you explain how you intend to reach customers and turn interest into revenue?
  • Legal and business structure: Have you considered the foundational business and intellectual property questions relevant to your startup?

The benefit of working with multiple advisors is the opportunity to examine your business from different perspectives. A market opportunity that looks attractive in a presentation still needs to make sense operationally, financially, and commercially.

GrowthCraft’s founder community and peer-learning opportunities can also give you a place to practice explaining your business, receive feedback, and refine your story before sharing it with potential investors.

The goal is to build a pitch deck that reflects a business you understand, a set of assumptions you can defend, and a plan you are prepared to execute.

Frequently Asked Questions About Startup Pitch Decks

1. How many slides should a startup pitch deck have?

A 10-slide core deck is a practical starting point for many early-stage startups. Some founders expand it to 12 slides to include a dedicated team slide and a more detailed vision or milestone slide. The appropriate length depends on your business and the purpose of the presentation.

2. What should a pitch deck include if my startup has no revenue?

An idea-stage or pre-revenue startup can focus on the customer problem, proposed solution, product prototype, market opportunity, business model, competitive alternatives, and founding team. Include evidence from customer interviews, prototype testing, pilot discussions, or other validation efforts where available. Be clear about what is proven and what remains an assumption.

3. Should I include financial projections in my pitch deck?

Yes, when you are seeking investment, a financial overview can help explain how the business may develop and what resources it needs. A simple three-year forecast is a useful starting point for many early-stage founders. Explain the assumptions behind revenue, expenses, hiring, and cash requirements rather than presenting projections as guaranteed outcomes.

4. What is the difference between TAM, SAM, and SOM?

TAM is the total addressable market for your product or service. SAM is the portion your business can serve based on its offering and operating model. SOM is the portion of that serviceable market you realistically expect to capture within a defined period. These measures help explain the size of the opportunity and the scale of your initial business goals.

5. What is the most important part of a startup pitch deck?

There is no single slide that matters equally for every startup. The deck needs to communicate a connected business case: a meaningful customer problem, a compelling solution, a credible market opportunity, and a team with a realistic plan for execution. The most important emphasis depends on what your startup has already demonstrated and what investors need to understand.

Final Checklist: Is Your Pitch Deck Ready?

Pitch deck readiness

0 of 11

  • I can explain what my company does in one clear sentence.
  • The customer problem is specific and supported by evidence.
  • My solution directly addresses that problem.
  • The product or prototype is easy to understand.
  • My market sizing assumptions are transparent and defensible.
  • I can explain who pays and how the business makes money.
  • I have a specific, evidence-based reason for why now.
  • I understand direct competitors and existing alternatives.
  • My traction metrics accurately reflect our stage.
  • My funding request, runway, milestones, and forecast are consistent.
  • I have practiced presenting the story and answering questions.

Conclusion

The best pitch deck outline is one that helps an investor understand your startup’s opportunity without making them work to connect the dots.

Start with a clear explanation of what you do. Show the problem, introduce your solution, demonstrate the product, and explain the market and business model. Then establish what makes the timing relevant, how you compare with alternatives, what progress you have made, and what you need to accomplish next.

For first-time founders, the real value of building a pitch deck is the thinking that happens along the way. Every slide gives you an opportunity to test an assumption, identify a gap, or make your business strategy clearer.

Use the outline as a working guide. Refine it as you learn more about your customers, product, and market. Resources such as GrowthCraft can help you work through those business questions with advisors and fellow founders, so your pitch becomes more than a presentation. It becomes a clearer plan for building your company.

Sources and Further Reading

These resources provide additional context for the pitch deck structure and examples discussed in this guide.

Writing a Business Plan : Sequoia Capital

A foundational guide covering company purpose, customer problem, solution, timing, market potential, competition, business model, team, financials, and vision.

Recommended Pitch Deck Ordering : University of Victoria, Gustavson School of Business

A comparison of observed pitch deck ordering and Sequoia’s recommended sequence.

A Practical Investor Deck Built From Sequoia’s Pitching Framework : Lunera

An independent adaptation discussing how founders can translate pitching principles into a practical investor presentation.

Sequoia Capital Pitch Deck Template (PDF) : Historical template reproduction

A circulated version of the familiar 10-section outline. Use it as a reference, rather than assuming it is a current official slide-design template.

The Best Pitch Deck Outline: A Step-by-Step Guide for First-Time Startup Founders Read More »

Scroll to Top